Serving Chicago • Cook County • Lake County • DuPage County

Renovations That Increase Home Value: Do They Raise Appraisal Value in Cook County?

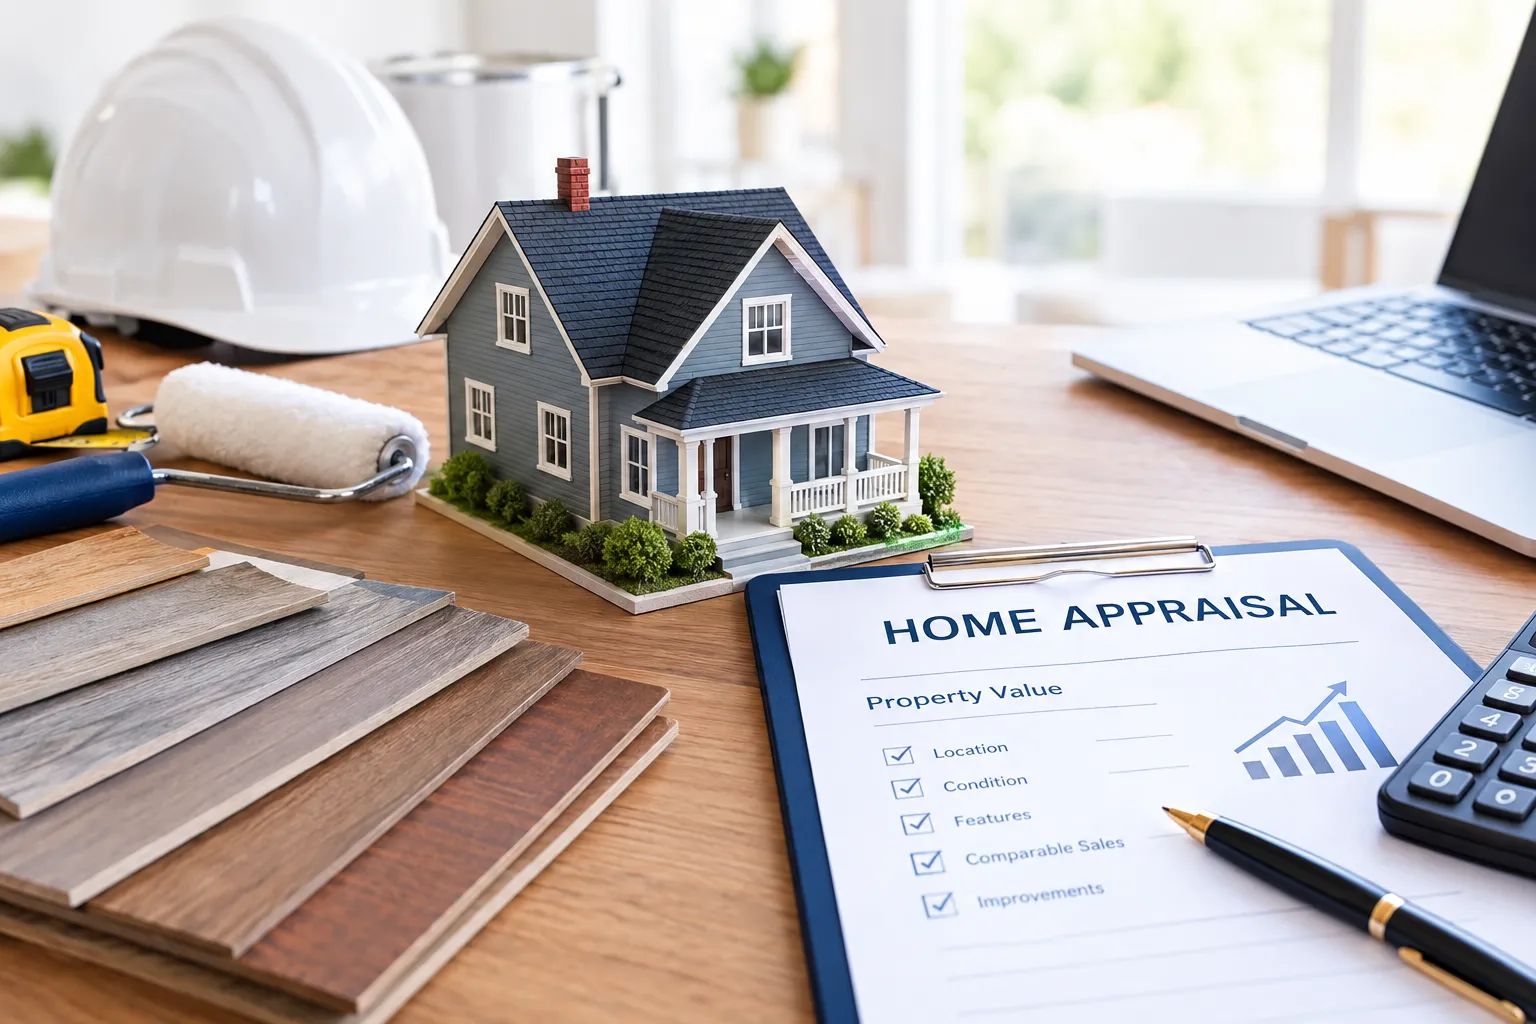
Home renovation materials and house model for property appraisal

Renovations that increase home value could make a home attractive, but they do not always increase its appraised value by the same amount as the renovation cost. 

This difference is important because the cost of renovation and market value aren’t identical. Understanding how renovations impact home appraisals can help you pick renovations that will improve your property as well as fit into what the market is like in your area.

Do Renovations Increase Home Appraisal Value?

Yes, renovations can boost the value of a home’s appraisal, but it depends on the nature and the quality of work. The appraiser will consider the condition of the home, its features, its location, as well as comparable sales, rather than just adding the renovation costs to the value of the property.

They can, especially when upgrades improve the home’s functionality, condition, or appeal. But the financial impact will differ from one property to another and from market to market.

Cost vs. Added Value

A $30,000 renovation does not automatically add $30,000 to the home’s appraised value. The appraised property value is determined by what the market will support through comparable properties, as well as other aspects of market value.

What Home Improvements Increase Appraisal Value?

Several home improvements that add value to an appraisal can make a property more competitive. Common examples of renovations that increase home value include:

  • Updated kitchens
  • Renovated bathrooms
  • Additional usable living space
  • Major system improvements
  • Quality flooring and interior updates
  • Exterior repairs and improvements

The answer to what home improvements increase appraisal value depends on the property and its local market. Practical improvements that are well completed and consistent with nearby homes generally have more relevance than highly personalized upgrades.

What Renovations Increase Home Appraisal Value the Most?

What renovations add value to a home appraisal can differ per home, but renovations that address outdated or inefficient areas can have a noticeable impact on the appraised value relative to similar homes. Upgrades to kitchens and bathrooms, additions of functional living space, and major repairs can all boost the value of a home during an appraisal.

Improvements With Limited Impact

Some projects may make a home more enjoyable without adding the same amount to its market value. Highly customized features, unusual luxury upgrades, and improvements that go well beyond neighborhood standards may have limited appraisal support.

Workmanship matters as well. Poorly completed projects or unfinished renovations can create concerns instead of adding value.

How Do Appraisers Evaluate Renovated Homes?

Appraisers look at the home’s current condition, features, quality, and completed improvements. They then compare the property with similar recently sold homes to develop a market-supported home appraisal.

The process generally includes:

  1. Reviewing the home’s size, layout, and condition.
  2. Identifying completed renovations.
  3. Considering the quality and function of improvements.
  4. Reviewing comparable sales.
  5. Accounting for meaningful differences between properties.
  6. Developing an opinion of market value.

This is central to understanding how renovations affect home appraisal. An improvement is more likely to influence value when comparable sales show that buyers in the market recognize it.
Home improvement checklist and model house showing potential value increase

Do Home Renovations Increase Appraised Value in Every Market?

No, whether renovations increase appraisal value depends partly on local market conditions. Buyers may prioritize updated kitchens in one neighborhood while placing more value on additional living space or overall condition in another.

Comparable sales are important here. If similar renovated homes consistently sell for more, those sales may provide stronger support for the improvement’s contribution to value.

For example, a practical kitchen update may bring an older home in line with nearby properties. An expensive custom kitchen may look impressive but have less appraisal impact if surrounding homes do not support the additional investment.

What to Do Before Starting a Renovation

Before choosing renovations that increase home value, consider these steps:

  1. Assess the property: Identify outdated areas, needed repairs, and functional problems.
  2. Review comparable homes: Look at the features offered by similar properties.
  3. Prioritize useful upgrades: Focus on condition, function, and durability.
  4. Check permit requirements: Keep required permits and approvals.
  5. Avoid over-improving: Consider the standards of homes in your neighborhood.
  6. Keep renovation records: Save receipts, permits, invoices, and project details.

Keep Records of Improvements

Good records document what changed and when the work was completed. Keep receipts, permits, contractor information, and before-and-after details organized for future reference.

Conclusion

Renovations that increase home value in Cook County may help raise the appraisal; however, it is not a one-to-one comparison between what is spent and what is gained. IAS residential research comparable homes for you, while making sure all improvements to the property are documented so they’re properly considered during the appraisal process.

Frequently Asked Questions

Do renovations increase home appraisal value?

Yes, renovations can add to a home’s appraised value when they improve its condition, functionality, or appeal and are supported by comparable sales in the local market. It is dependent on the extent of improvements made on the property.

What home improvements increase appraisal value the most?

Bathroom and kitchen updates, addition of living space, as well as major repairs and upgrades to the home’s equipment can increase appraisal value. The impact on appraisal value depends on the features and sale prices of similar homes in the same area. 

Do renovations increase property value?

Renovations can increase property value, but the amount depends on the type and quality of the improvements and local market conditions 

How do renovations affect home appraisal?

Remodeling can affect the appraisal by improving the condition, quality, function, and even the features of the property, which will be compared to similar sales to establish a market value.

Do home renovations increase appraisal value dollar for dollar?

The cost of renovations is not immediately added to an appraised price. A property appraisal will reflect its market value instead of simply paying the homeowner for improvement costs. 

What renovations increase home appraisal value?

Bathroom and kitchen renovations and living spaces that are usable, major repairs, and high-quality upgrades that increase home value. The most effective enhancements are those that are supported by local demand from buyers as well as comparable homes. 

Does a remodeled kitchen increase appraisal value?

A renovated kitchen can boost the appraised value in the event that it improves functionality, quality, condition, and appeal. However, a high-end custom-designed kitchen might not add its entire value to the appraised value of your home. 

Does adding a bathroom increase home appraisal value?

Yes, adding a bathroom can boost a home’s appraised value if it improves functionality and meets market expectations. 

Can over-improving a home limit appraisal value?

Yes, it is possible to limit the financial benefits of a remodel. If the home is better than comparable houses in the area, the market may not be able to fully fund the investment. 

Should homeowners renovate before an appraisal?

Not necessarily. The homeowners should make improvements according to the needs of the property and expectations of the market, rather than just trying to boost the value of their property.
Renovations That Increase Home Value: Do They Raise Appraisal Value in Cook County?

Renovations that increase home value could make a home attractive, but they do not always increase its appraised value by the same amount as the renovation cost. 

This difference is important because the cost of renovation and market value aren’t identical. Understanding how renovations impact home appraisals can help you pick renovations that will improve your property as well as fit into what the market is like in your area.

Do Renovations Increase Home Appraisal Value?

Yes, renovations can boost the value of a home’s appraisal, but it depends on the nature and the quality of work. The appraiser will consider the condition of the home, its features, its location, as well as comparable sales, rather than just adding the renovation costs to the value of the property.

They can, especially when upgrades improve the home’s functionality, condition, or appeal. But the financial impact will differ from one property to another and from market to market.

Cost vs. Added Value

A $30,000 renovation does not automatically add $30,000 to the home’s appraised value. The appraised property value is determined by what the market will support through comparable properties, as well as other aspects.

What Home Improvements Increase Appraisal Value?

Several home improvements that add value to an appraisal can make a property more competitive. Common examples of renovations that increase home value include:

  • Updated kitchens
  • Renovated bathrooms
  • Additional usable living space
  • Major system improvements
  • Quality flooring and interior updates
  • Exterior repairs and improvements

The answer to what home improvements increase appraisal value depends on the property and its local market. Practical improvements that are well completed and consistent with nearby homes generally have more relevance than highly personalized upgrades.

What Renovations Increase Home Appraisal Value the Most?

What renovations add value to a home appraisal can differ per home, but renovations that address outdated or inefficient areas can have a noticeable impact on the appraised value relative to similar homes. Upgrades to kitchens and bathrooms, additions of functional living space, and major repairs can all boost the value of a home during an appraisal.

Improvements With Limited Impact

Some projects may make a home more enjoyable without adding the same amount to its market value. Highly customized features, unusual luxury upgrades, and improvements that go well beyond neighborhood standards may have limited appraisal support.

Workmanship matters as well. Poorly completed projects or unfinished renovations can create concerns instead of adding value.

How Do Appraisers Evaluate Renovated Homes?

Appraisers look at the home’s current condition, features, quality, and completed improvements. They then compare the property with similar recently sold homes to develop a market-supported value.

The process generally includes:

  1. Reviewing the home’s size, layout, and condition.
  2. Identifying completed renovations.
  3. Considering the quality and function of improvements.
  4. Reviewing comparable sales.
  5. Accounting for meaningful differences between properties.
  6. Developing an opinion of market value.

This is central to understanding how renovations affect home appraisal. An improvement is more likely to influence value when comparable sales show that buyers in the market recognize it.

Do Home Renovations Increase Appraised Value in Every Market?

No, whether renovations increase appraisal value depends partly on local market conditions. Buyers may prioritize updated kitchens in one neighborhood while placing more value on additional living space or overall condition in another.

Comparable sales are important here. If similar renovated homes consistently sell for more, those sales may provide stronger support for the improvement’s contribution to value.

For example, a practical kitchen update may bring an older home in line with nearby properties. An expensive custom kitchen may look impressive but have less appraisal impact if surrounding homes do not support the additional investment.

What to Do Before Starting a Renovation

Before choosing renovations that increase home value, consider these steps:

  1. Assess the property: Identify outdated areas, needed repairs, and functional problems.
  2. Review comparable homes: Look at the features offered by similar properties.
  3. Prioritize useful upgrades: Focus on condition, function, and durability.
  4. Check permit requirements: Keep required permits and approvals.
  5. Avoid over-improving: Consider the standards of homes in your neighborhood.
  6. Keep renovation records: Save receipts, permits, invoices, and project details.

Keep Records of Improvements

Good records document what changed and when the work was completed. Keep receipts, permits, contractor information, and before-and-after details organized for future reference.

Conclusion

Renovations that increase home value in Cook County may help raise the appraisal; however, it is not a one-to-one comparison between what is spent and what is gained. IAS residential research comparable homes for you, while making sure all improvements to the property are documented so they’re properly considered during the appraisal process.

Frequently Asked Questions

Do renovations increase home appraisal value?

Yes, renovations can add to a home’s appraised value when they improve its condition, functionality, or appeal and are supported by comparable sales in the local market. It is dependent on the extent of improvements made on the property.

What home improvements increase appraisal value the most?

Bathroom and kitchen updates, addition of living space, as well as major repairs and upgrades to the home’s equipment can increase appraisal value. The impact on appraisal value depends on the features and sale prices of similar homes in the same area. 

Do renovations increase property value?

Renovations can increase property value, but the amount depends on the type and quality of the improvements and local market conditions 

How do renovations affect home appraisal?

Remodeling can affect the appraisal by improving the condition, quality, function, and even the features of the property, which will be compared to similar sales to establish a market value.

Do home renovations increase appraisal value dollar for dollar?

The cost of renovations is not immediately added to an appraised price. A property appraisal will reflect its market value instead of simply paying the homeowner for improvement costs. 

What renovations increase home appraisal value?

Bathroom and kitchen renovations and living spaces that are usable, major repairs, and high-quality upgrades that increase home value. The most effective enhancements are those that are supported by local demand from buyers as well as comparable homes. 

Does a remodeled kitchen increase appraisal value?

A renovated kitchen can boost the appraised value in the event that it improves functionality, quality, condition, and appeal. However, a high-end custom-designed kitchen might not add its entire value to the appraised value of your home. 

Does adding a bathroom increase home appraisal value?

Yes, adding a bathroom can boost a home’s appraised value if it improves functionality and meets market expectations. 

Can over-improving a home limit appraisal value?

Yes, it is possible to limit the financial benefits of a remodel. If the home is better than comparable houses in the area, the market may not be able to fully fund the investment. 

Should homeowners renovate before an appraisal?

Not necessarily. The homeowners should make improvements according to the needs of the property and expectations of the market, rather than just trying to boost the value of their property.
What Is a Red Flag on an Appraisal? A Chicago Homeowner’s Guide

A residential appraisal provides an independent opinion of a property’s market value. In Chicago, IL, appraisals are commonly used when buying or selling a home, refinancing a mortgage, settling an estate, handling a divorce, or making other important real estate decisions.

During an appraisal, a professional appraiser evaluates the property’s condition, features, location, improvements, and recent comparable sales. Certain conditions can raise questions about a property’s value or marketability. These issues are commonly referred to as appraisal red flags.

Understanding these red flags can help Chicago homeowners prepare for an appraisal and avoid unexpected issues.

What Is a Red Flag on a Home Appraisal?

An appraisal red flag is a property condition, discrepancy, or circumstance that may require additional consideration when determining market value.

A red flag does not automatically mean that a home will receive a low appraisal. Instead, it indicates that an issue may need to be investigated, documented, repaired, or carefully considered as part of the valuation process.

For example, an appraiser may notice an apparent discrepancy in the property’s square footage, an unusual addition, deferred maintenance, or a lack of comparable sales. The significance of the issue depends on the property and the available market evidence.

Common Appraisal Red Flags in Chicago

1. Deferred Maintenance and Property Damage

Visible maintenance problems can affect a property’s condition and marketability. Common examples include:

  • Damaged roofing
  • Water intrusion or staining
  • Broken windows
  • Peeling exterior materials
  • Deteriorated flooring
  • Plumbing or electrical concerns
  • Foundation or structural issues

Chicago homes can experience additional wear from seasonal weather, including freezing temperatures, snow, ice, and moisture. Keeping up with necessary maintenance can help protect both the condition and marketability of a residential property.

2. Unpermitted Renovations or Additions

Unpermitted work can create questions during a Chicago home appraisal. Major renovations, finished basements, room additions, converted garages, decks, and other improvements may require appropriate approvals or documentation.

If a homeowner has completed significant improvements, keeping records, permits, invoices, and other relevant documentation can help provide clarity about the work.

An appraiser must determine how the property’s characteristics and improvements should be considered in the valuation based on the assignment and available market information.

3. Incorrect Square Footage or Property Details

Incorrect property information is another potential appraisal red flag.

Differences involving living area, lot size, bedrooms, bathrooms, finished basement space, or other property characteristics may require clarification.

This is particularly important in Chicago, where residential properties can vary considerably by neighborhood and housing type. A classic Chicago bungalow, condominium, two-flat, townhome, or single-family residence may have very different characteristics that affect how comparable properties are selected.

4. Significant Structural or Safety Concerns

Serious visible structural or safety issues can have a greater impact on an appraisal than ordinary cosmetic problems.

Examples may include significant foundation damage, unsafe stairs or railings, substantial water damage, or other apparent conditions that could affect the property’s usability or marketability.

An appraisal is not a substitute for a professional home inspection. If an appraiser observes a condition that requires specialized evaluation, an additional inspection may be appropriate.

5. Unusual Property Features

Chicago has a diverse housing market, with properties ranging from historic homes and Chicago bungalows to condominiums, townhomes, multi-unit buildings, and newer construction.

Unique features are not necessarily negative. However, unusual layouts, extensive renovations, atypical additions, or other characteristics may make it more difficult to find directly comparable properties.

The appraiser may need to analyze several comparable sales and make appropriate adjustments based on differences between the properties.

6. Limited or Poor Comparable Sales

Comparable sales, often called “comps,” are an important part of residential property valuation.

A strong appraisal generally requires analysis of recent sales that are reasonably comparable to the subject property. In some Chicago neighborhoods, there may be plenty of recent sales. In others, finding truly comparable properties can be more challenging.

Factors such as neighborhood, property size, age, condition, design, lot characteristics, and location can influence which sales are appropriate for comparison.

Simply using the highest or lowest recent sale price does not provide a reliable indication of a property’s market value.

Do Appraisal Red Flags Automatically Lower Home Value?

No. An appraisal red flag does not automatically reduce a property’s value.

The impact depends on the type and severity of the issue, the property’s overall condition, buyer expectations, and evidence from the local Chicago real estate market.

For example, outdated paint or older kitchen finishes may have a different impact than significant structural damage. Similarly, an unusual property feature may not reduce value if buyers in the local market consider it desirable.

A qualified appraiser analyzes the available evidence before determining how individual characteristics affect the final opinion of value.

How Chicago Homeowners Can Prepare for an Appraisal

Before a residential appraisal, homeowners can take several practical steps:

  • Address obvious maintenance problems.
  • Keep documentation for major renovations and improvements.
  • Make sure the appraiser can access all areas of the property.
  • Verify basic property information for accuracy.
  • Provide information about significant upgrades when appropriate.
  • Keep permits and renovation records available.
  • Make sure garages, basements, attics, and other relevant areas are accessible.

You do not need to make expensive cosmetic changes simply to prepare for an appraisal. The goal is to make the property’s condition and features clear and accessible.

Choose a Professional Chicago Residential Appraisal Service

Whether you are refinancing a mortgage, purchasing a Chicago home, selling property, settling an estate, or dealing with another real estate matter, a professional appraisal can provide an independent opinion of market value.

IAS Residential Appraisal Services provides professional residential appraisal services in Chicago, IL, helping property owners and real estate professionals obtain well-supported valuations based on the property’s characteristics and relevant market data.

From Chicago single-family homes and condominiums to other residential properties throughout the area, understanding potential appraisal red flags can help you approach the valuation process with greater confidence.

If you need a residential property appraisal in Chicago, IL, IAS Residential Appraisal Services can help provide the professional valuation information you need for your real estate decision.

10 Factors That Affect Property Value: What Homeowners Should Know in DuPage County

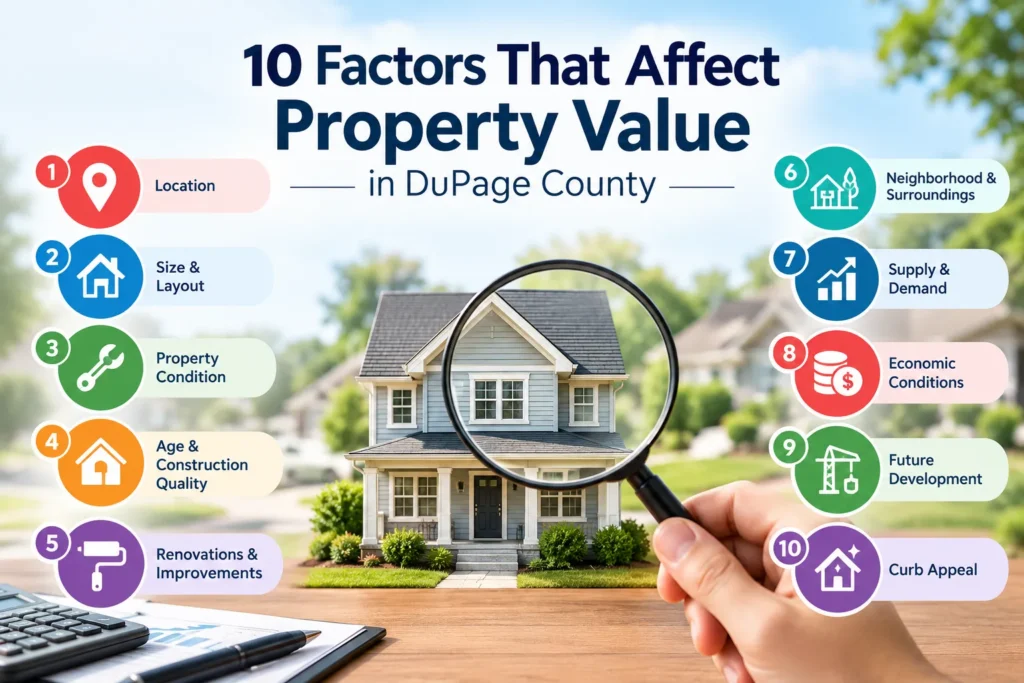
10 factors that affect property value in DuPage County, including location, condition, renovations, demand, and curb appeal

If you own a house, you might have asked yourself what is the value of your house? Knowing what affects the value of a home can help make informed decisions when either selling or refinancing a home or just protecting it.

So, what determines a homes value? It’s not just one thing. It is a location decision, it’s a size decision, it’s a condition decision, it’s a features decision, it’s a neighborhood decision, it’s a demand decision, and it’s a market decision. There are things we can control and some things we can’t.

Knowing the factors that affect property value in DuPage County can help you concentrate on the enhancements and choices that are important to you.

What Are the 10 Factors That Affect Property Value?

1. Location

One of the biggest factors that influence home value is location. Schools, transportation, workplaces, shopping, parks and other conveniences are factors buyers may consider when shopping for nearby schools.

Strong demand can be generated even if a home is not the newest or largest. House location and surroundings are important aspects of any property valuation, which is why you should consider these factors when looking for a house.

2. Size and Layout

Although square footage is important, usable square footage is even more important. Home buyers consider bedrooms, bathrooms, storage, parking, outdoors space and room flow.

These property characteristics are key in deciding if a house is right for a prospective buyer. Sometimes a smaller home with a functional layout is more appealing than a larger home with poor design.

3. Property Condition

How much does condition affect house price? It can have a significant impact. The roof, plumbing, electrical, HVAC, flooring, kitchen, bathrooms and exterior are typical features buyers will notice.

A neat home can inspire buyers, and extensive repairs can be a part of the what lowers property value will need to budget for repairs in the future.

4. Age and Construction Quality

Don’t judge the value of something by its age. Older homes can still be desirable, if they are well-maintained, built of quality materials, and are older.

The quality of construction, energy efficiency, the durability of the property, and condition of the major systems are among the important characteristics of the value in real estate that influence the long term usefulness of the property.

5. Renovations and Improvements

Renovations can contribute to property value increase,especially if they provide a greater level of functionality and/or address dated rooms or spaces.

A home can be more attractive if it has up-to-date kitchens, bathrooms, energy-saving features and more usable space. But, homeowners should not take it for granted that all high dollar improvements will return the same amount.

With regard to what makes property value increase, think about upgrades that are appropriate for the property and desirable by the local community.

6. Neighborhood and Surroundings

The exterior area can be just as significant as the interior space. Amenities, such as good infrastructure and green spaces, and well-maintained streets can help meet buyer demand.

Too many cars, too much noise, too little maintenance, or too many untidy neighbors can be examples of what hurts property value.

7. Supply and Demand

Property prices can rise or fall rapidly, depending on the local market. Sellers can get better offers when there is competition among multiple buyers for a few homes. If there are numerous homes on the market, sellers may have to offer the home at a lower price.

That’s why the price of a house can fluctuate regardless of the condition of the house itself.

8. Economic Conditions

Buyers’ affordability can be influenced by mortgage rates, employment, inflation and economic confidence.

The rise in mortgage rates could limit affordability, and lower rates could stimulate demand. These conditions can affect the value of a property’s market.

9. Future Development

Convenience provided with new roads, schools, parks, transportation and shopping areas can help increase property values.

But development can be detrimental too. An excessive traffic and noise volume or other issues associated with a project may decrease the value of nearby properties.

10. Curb Appeal

First impressions matter. A home’s exterior appearance can be impacted by landscaping, exterior paint, lighting, entrance, driveway and general maintenance.

Curb appeal is not what makes a house worth more, but it can make the house more attractive to prospective buyers.

Property value factors in DuPage County shown around a home, including location, size, condition, renovations, demand, and development

What Lowers Property Value?

Common concerns include:

  • Poor maintenance
  • Structural problems
  • Damage to the roof or water damage.
  • Outdated major systems
  • Poor curb appeal
  • Too much noise and/or traffic
  • Limited parking
  • Unattractive surroundings
  • Declining neighborhood conditions

The effect is based upon the home, the price of the repair and local buyer anticipations.

What Makes Property Value Increase?

So, what makes property value increase? Some regular maintenance, practical upgrades, nice curb appeal, energy efficiency, and neighborhood upgrades can all do a little.

Homeowners should concentrate on improvements which will help to solve a genuine problem or increase the usefulness and attractiveness of the property. But it’s not always the case that you’ll get a higher price for spending lots of money on the personal touches.

How Can You Estimate Your Home’s Value?

The factors that affect property value provide a useful starting point, but the market value of your property will be influenced by local conditions.

Review similar home sales in the area, similar listings, property condition, size, features and neighborhood demand. A better estimate can be done by using the services of a real estate professional or appraiser who can compare your home with other homes in your neighborhood.

Conclusion

Understanding the factors that affect property value in DuPage County, you’ll be able to make better choices. Buyer value is subject to the influence of location, condition, size, layout, renovations, neighborhood quality, demand, economic conditions and future development.

Location is one of those things that can’t be changed. Others like maintenance, presentation, and some improvements, are under your control. Understanding the distinction can assist you in spending your cash on a place where it will be most valuable.

Frequently Asked Questions

What are the main factors that affect property value?

The main factors that affect property value include location, size, condition, layout, construction quality, renovations, neighborhood, demand, and economic conditions.

What determines a homes value?

What determines a homes value is a combination of its features, condition, location, comparable sales, buyer demand, and current market conditions.

What makes property value increase?

What makes property value increase can include proper maintenance, useful renovations, energy efficiency, curb appeal, neighborhood improvements, and strong buyer demand.

What lowers property value?

Poor maintenance, structural problems, outdated systems, water damage, excessive noise, poor surroundings, and declining neighborhood conditions can contribute to what lowers property value.

How much does condition affect house price?

How much does condition affect house price depends on the property, but major repairs can reduce buyer interest and cause buyers to account for repair costs.

What property characteristics affect value?

Important property characteristics include size, bedrooms, bathrooms, layout, parking, storage, construction quality, energy efficiency, and major systems.

Why does location affect property value?

House location and surroundings influence convenience and demand. Schools, transportation, amenities, safety, traffic, and nearby development can all affect desirability.

What hurts property value the most?

There is no single answer to what hurts property value, but major structural issues, poor maintenance, undesirable surroundings, and weak demand can have a significant effect.

Can renovations increase property value?

Yes. Practical improvements can support property value increase, especially when they improve functionality, condition, efficiency, or features buyers want.

What are the characteristics of value in real estate?

The characteristics of value in real estate include utility, desirability, scarcity, location, condition, functionality, and market demand.

Retrospective Date-of-Death Appraisal: What You Need to Know

Retrospective Date-of-Death Appraisal

When a homeowner dies, real estate might need a value established as of the death date instead of the current one. A retrospective appraisal estimates a property’s market value as of a specific date in the past, based on the market conditions and available evidence from that time. 

This service helps in estate administration, dispute resolution, tax filings, probate, inheritance, and other matters. A retrospective appraisal differs from a current one in that it considers the market environment as of a particular date rather than today.

What Does a Retrospective Date-of-Death Appraisal Include? 

A retrospective appraisal refers to an appraisal type used to estimate the value of a property at some point in the past, usually at time when a certain owner dies. In this case, an appraiser uses the information regarding the location, size, condition, improvements of the property, together with comparable sales and market conditions at the time of death to value the property.

Historic Valuation of Property: Determines the value of a property as of a specific date in the past. 

Date of Death Valuation: Establishes property value as of an owner’s death for estate purposes. 

Comparable Sales Research: Analyzes sales of similar real estate in a historical context. 

Retrospective Appraisal Reports: Provides an appraisal report that covers the specifics of the property, the comparable sales, and the resulting value conclusion. 

Estate & Legal Support: Offers support to lawyers, executors, accountants, and other professionals involved in the settlement by presenting well-documented proof of a property’s characteristics on a certain date. 

Why is a Date-of-Death Appraisal Important? 

A date of death appraisal is required when it comes to the property to be distributed from the estate of the deceased. It is highly likely that a particular piece of real estate has to be divided among the children or other close relatives. Suppose it was purchased in March 2021, but the hearing is set in 2026 – the value of the house might have increased significantly since then.

When is a Retrospective Appraisal Needed? 

A retrospective property valuation may be required for estate, inheritance, probate, tax, capital gains, divorce appraisal, or any other purpose pertinent to the matter. For example, if the owner passed away in 2020 and the house was sold in 2024, the value would be needed to know for 2020.

How Does a Retrospective Property Appraisal Work? 

The appraisal process begins by establishing the effective date and specific purpose of the assignment. Next, the property’s history and current condition are examined and considered. Comparable sales are then analyzed based on factors such as the sale date, location, size, condition, and improvements of the subject property.

In addition, historical abstracts, permits, assessments, and market data shall be reviewed and considered in determining value estimates

Retrospective Appraisal

What is Included in a Retrospective Appraisal Report? 

A retrospective appraisal report identifies the property, effective date, and the appraisal use. It also covers the data and methods used, comparable sales, market evidence, and why a particular value conclusion makes sense.

A reputable company works with you to ensure that the report addresses the intended purpose and gives sufficient information for the executor, attorney, accountant, or other designated recipient.

How Much Does a Retrospective Appraisal Cost? 

A professional appraisal service determines the fee based on several variables associated with the task. 

Factors That May Affect the Fee

  • Size and type of property
  • Location
  • Time of the valuation
  • Availability of historical data
  • Comparable sales
  • Complexity of the property
  • Length of research required
  • Specific use for the appraisal
  • Reporting level

How to Choose a Retrospective Appraiser 

Only experienced professionals can handle historical valuations that require identifying and analyzing relevant data. It is essential to note the intended use of the appraisal when working with an expert. 

Conclusion

A retrospective appraisal helps to establish a professional opinion of value as of a specific date in the past. A date-of-death appraisal establishes the property’s market value as of the applicable valuation date associated with the owner’s death. This estimate considers the state of the market, comparable sales, and other factors influencing the value to give a reasonable indication of what real estate sold for in the past.

As a result, the work becomes helpful for court cases, inheritance matters, taxes, financial records, probate, and more.

Frequently Asked Questions

What is the difference between a current appraisal and a retrospective appraisal?

An appraisal focuses on the current value, while a retrospective appraisal determines the value as of a specific date in the past. 

Is a date of death appraisal always required for an estate?

Not necessarily. It depends on various factors including an estate’s needs and tax requirements. 

How far back can a property be valued?

It depends on the property and the availability of historical data and comparable sales. 

Can the valuation be used for tax purposes?

It depends on the specific requirements. A tax attorney should be consulted to determine if it will suffice for the intended purpose. 

What documents can help the appraiser?

Prior appraisals, photographs, purchase agreements, tax records, permits, and other documents related to the property can be useful. 

Why does the cost vary between properties?

Several factors contribute to the final rate including the length of research, property type, and complexity of the appraisal. 

How long does a historical valuation take?

The time needed to complete the task varies depending on multiple factors including the type of property, research, and market.

Can You Use Your House as Bail Bond Collateral?

House used as bail bond collateral with a bail agreement and gavel

Depending on the state laws, the value of the property, the equity, and type of bail bond, sometimes a house can be used as Bail Bond Collateral. Financial security can be established for the bond and legal ownership can be demonstrated to accept a home.

It is important to understand the requirements, paperwork, risks and process before using a house.

What is Bail Bond Collateral?

Bail bond collateral is an asset pledged to secure a bail bond. The collateral can be released when the defendant complies with the conditions of release. Common forms include:

  • Real estate or other valuable property 
  • Land
  • Vehicles
  • Bank accounts
  • Other valuable assets

Can You Use a House as Collateral for Bail? 

Absolutely, bail can be granted using a house as collateral if the conditions outlined in the local rules are met. The Court or bail provider might take into account:

  • Property value
  • Available equity
  • Existing mortgage
  • Property liens
  • Ownership status
  • Bail amount

If homeowners have a large mortgage or a lien on the home, there may not be enough home equity available.

What are the requirements for the property bond for bail?

There are state and court requirements for property bonds. In general, it should be of substantial value, and a property valuation may be needed to establish how much the property is worth.

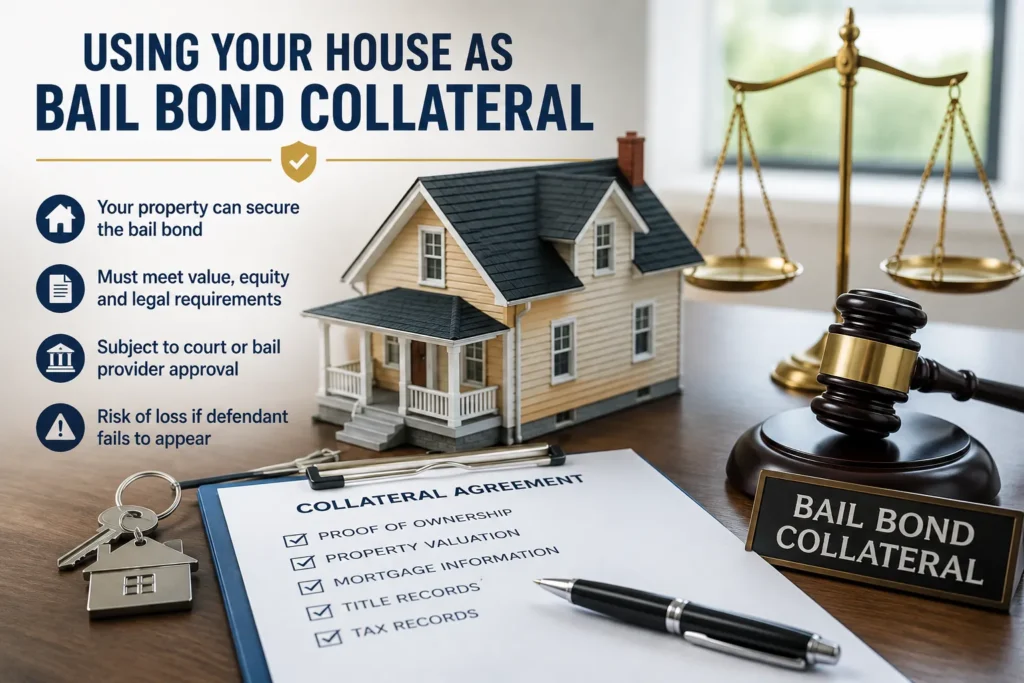
Typical Requirements Include:

RequirementPurpose
Proof of ownershipConfirms the legal owner
Property valuationEstablishes property value
Mortgage detailsShows outstanding debt
Title recordsIdentifies ownership and claims
Tax recordsProvides property information

How to Put Up Property for Bail

The first step in learning how to put up property for bail is to confirm that real estate is accepted for a property bond in your jurisdiction. If you’re unfamiliar with the overall bail process, understanding how bail bonds work can also help clarify where collateral fits into the process.

The overall process is:

  1. Establish that property bonds are allowed.
  2. Check ownership, equity in the property.
  3. Submit necessary paperwork.
  4. Sign the collateral agreement.
  5. Comply with court or bail provider’s filing requirements.
  6. Ensure that the conditions for releasing the property are met.

This process may differ depending on the jurisdiction.

House used as bail bond collateral with property valuation and legal documents

What Documents are Needed for Bail Bond Approval? 

The documents required for bail bond approval vary by jurisdiction, property type, and bond provider. Common types of bail bond paperwork include: 

  • Government-issued ID
  • Property deed
  • Property tax records
  • Mortgage statement
  • Title information
  • Property valuation
  • Lien information
  • Proof of ownership
  • Signed collateral documents

Preparing documents in advance can prevent any delays.

What Happens to the Property After Bail Is Posted? 

If a house is accepted as bail bond collateral, a legal claim or security interest may be placed on the property, depending on the jurisdiction and bond arrangement. The owner should be aware of:

  • Whether the property can be sold
  • Whether refinancing is restricted
  • When the collateral will be released
  • What happens if the defendant fails to appear

These conditions should be clearly stated in the written contract.

What Happens If the Defendant Misses Court? 

If the defendant fails to appear in court, the bail may be forfeited, and the person who provided the Bail Bond Collateral could face financial consequences. If a house was pledged as collateral, the outcome depends on state law, the bond agreement, and the court’s decision. Review the agreement carefully to understand what could happen to the property.

Can You Get Your Bail Bond Collateral Back? 

Collateral is often released once the bail obligation is met. But there may be more paperwork involved or a court order.

  • What triggers the release
  • Who handles the release paperwork
  • How long the process may take
  • What happens if the case is dismissed or completed

Using a home as bail bond collateral can involve significant financial risk. Before pledging the property, carefully review the agreement, understand the conditions for releasing the collateral, and know what could happen if the defendant fails to meet the bond requirements.

Conclusion: 

Using a house for bail may be possible when the property meets local requirements and has enough equity. Bail Bond Collateral should be considered carefully because pledging a home creates financial obligations if the defendant fails to comply with the bond.

Always check the specific requirements with the relevant court, attorney, or licensed bail professional before using property to secure bail.

Frequently Asked Questions

Can a house be used as Bail Bond Collateral? 

A house can be eligible if local law allows for property bond requirements and the property is of adequate value, equity, and documentation to meet the bail requirement.

Does the house need to be paid off?

No. A mortgaged property can be considered if sufficient equity is left after subtracting the amount of the mortgage and other claims to the property.

Is anyone else’s house acceptable as bail?

In certain cases, a different person may make a bail bond for a defendant. The proprietor should be able to meet the necessary requirements and must assume financial liability.

What is the effect if the defendant does not appear in court?

Failure to show up in court may result in the forfeiture of bail and other legal penalties. The forfeiture might impact property pledged as security.

Which documents are required with a property bond?

Some of the most common documents are deeds, proof of ownership, records of property taxes, mortgage details, title documents, valuation documents, and signed legal agreements.

Can property with a mortgage qualify?

If the property still has substantial equity, it could also be allowed if the mortgage and any other liens are taken into account.

Is this valid if more than one owner pledges the same property?

Several owners might be able to pledge a property, but consent and signing of necessary papers from all the required owners may be necessary.

What is the length of the bail collateral?

Generally, collateral will stay in place until the bail obligation is satisfactorily addressed and any necessary bail process has occurred.

Can a pledged house be sold?

Selling or refinancing a property used as collateral may require approval or additional steps. The collateral agreement should be reviewed before making changes.

Is using a home as bail collateral safe?

It can involve significant financial risk. If the defendant fails to meet the bond conditions, the property owner could face financial consequences depending on the applicable law and agreement.

What Heirs Should Know Before Selling an Inherited Home

Checklist showing key steps heirs should know before selling an inherited home, including probate, taxes, property appraisal, and sale preparation.

Inheriting a house often feels like a strange mixture of emotions. On one hand, you are dealing with grief and the loss of someone close. On the other hand, you are suddenly responsible for a property that might be in another city, full of memories, and possibly in need of serious repairs. It is a lot to handle.

If you have decided that you want to sell inherited house, you are not alone. Many heirs choose to sell because they cannot afford the upkeep, they live elsewhere, or because dividing the property among multiple siblings is just too complicated. However, selling an inherited home is not the same as selling your own primary residence. The process is layered with legal steps, tax rules, and family dynamics that you simply cannot ignore.

Before you put up that For Sale sign, there are some crucial things you need to know to sell inherited house. This guide walks you through the practical steps, the taxes you might face, and the best ways to handle the entire process.

Establish Who is in Charge of the Estate

The very first thing you need to figure out is whether you have the legal right to sell the property. If the house is in a living trust, the process is usually smooth. The named trustee can typically sell the property immediately without needing court approval. If the house was owned jointly with rights of survivorship, the surviving owner inherits the property automatically.

This court process can take anywhere from a few weeks to over a year, depending on your state and the complexity of the estate. If you are dealing with multiple heirs, you will need to nominate a representative to handle the sale to sell inherited house.

The Financial Reality and Tax Implications

When you sell inherited property, you need to be prepared for the tax man. This is where many people get confused, thinking they will owe a fortune on the sale. Usually, this is not the case, but you need to know the rules.

The most important concept here is the stepped-up basis. This is a significant tax break for heirs. When you inherit a house, the tax basis is not what the deceased originally paid for it. Instead, the IRS resets the value of the house to its fair market value of inherited property. Imagine your parents bought a house for $50,000 in 1980, but it was worth $300,000 when they passed away. Your cost basis becomes $300,000.

If you decide to sell inherited house for $310,000, your taxable capital gain is only $10,000. If you sell it shortly after inheriting it, you will likely owe very little to no capital gains tax. This stepped-up basis only applies to inherited property. It does not apply to property that was gifted to you while the person was still alive .

How is Inherited Property Taxed When Sold?

Inherited property tax implications mostly concern capital gains. If you hold onto the house for years and it goes up in value, you will pay tax on the profit over the stepped-up basis. According to the IRS, inherited property is always considered long-term capital gains, regardless of how long you hold it, which gives you a better tax rate.

It is highly recommended to get a professional appraisal of the property dated as of the day the owner passed away. This appraisal is your proof of the stepped-up basis in case the IRS asks questions later.

There may also be estate taxes or inheritance taxes depending on the total value of the estate and where you live. However, federal estate taxes only apply to estates worth over $13.6 million, so this does not affect most people who sell inherited house.

Person reviewing a selling an inherited home checklist with estate documents, home appraisal report, taxes, and planning materials on a desk.

Challenges When Selling Inherited Property With Multiple Heirs

Selling an inherited property can get very stressful when you are doing it with siblings or other relatives. It is common for multiple heirs to inherit a property together. This can cause problems because not everyone agrees on what to do. One sibling might want to sell quickly for cash, while another wants to hold onto it for sentimental reasons, or one might want to renovate before selling while another wants to sell it as is.

Clear communication is critical to sell inherited house. You need to agree on a timeline, a method of sale, and how to handle offers. If the family cannot agree, you might need to bring in a mediator to help you reach a consensus. If things get really bad and no one can agree, you might have to deal with a partition action. This is a civil lawsuit where one heir forces the sale of the property through the court system. This is usually a last resort because it is expensive and time-consuming .

Preparing the House for the Market

Once you have the legal authority and have talked to the other heirs about taxes, you need to get the house ready. The process of selling an inherited home is just as emotional as it is logistical. The first job is usually the hardest: clearing out the house. It is a slow process, so do not try to do it all in one day. You can hire an estate sale company to help sell the bigger items or donate the rest .

When it comes to repairs, you want to tread carefully. You do not need to do a full renovation. Upgrading the kitchen or bathrooms usually does not get you your money back in a sale. Instead, focus on cosmetic fixes that make the home look well-maintained. Things like deep cleaning, painting the walls a neutral color, and fixing up the landscaping can make a big difference to sell inherited house.

Your Options To Sell Inherited House 

You have a few choices on how to sell an inherited house. You can list it on the open market with a real estate agent. This is often the best way to get the highest price, but it takes time. You will have to deal with showings, wait for a buyer to get financing, and potentially pay for holding costs like utilities and taxes while you wait .

Alternatively, you can sell the house to a cash buyer. Companies that buy houses for cash usually buy them as-is. This means you can skip the repairs, the cleaning, and the staging. You can often close within a week or two. The trade-off is that you might get a lower price than you would on the open market, but you get certainty and speed..

The Role of Professionals

Trying to navigate the sale of an inherited house on your own is usually a mistake. The process involves legal and tax rules that change depending on where you live. You should work with a real estate agent who specializes in probate sales if you choose the traditional route. In many cases, you should also speak with a probate attorney to make sure the paperwork is filed correctly and the title is cleared .

Frequently Asked Questions

Do I have to pay taxes when I sell inherited house?

Usually, you pay capital gains tax only on the profit above the fair market value at the time of inheritance (stepped-up basis). If you sell quickly, the tax is often minimal. You do not generally pay tax just for receiving the inheritance.

How is the stepped-up basis calculated?

The stepped-up basis is the home’s fair market value as of the date of the previous owner’s death. This is your starting value for tax purposes.

Can I sell an inherited house if it is in probate?

Yes, but you usually need court approval for the final sale. The executor or personal representative usually handles the sale with court oversight.

What happens if siblings disagree on selling an inherited house?

This is the most common dispute. If you cannot agree, you can try hiring a mediator. If that fails, a sibling could file for a partition action to force a sale in court.

Do I have to pay off the mortgage before selling?

Not before you sell, but the mortgage must be paid off at the closing. The title company will use the proceeds of the sale to pay off the existing mortgage and any other liens.

Is it better to sell an inherited house as-is or renovate?

It depends on your timeline and funds. For a traditional sale, focus on cosmetic fixes. If you want speed and have no cash for repairs, selling as-is to a cash buyer might be better .

What is the tax difference between inheriting a house and receiving it as a gift?

This is crucial. Inherited property gets a stepped-up basis, resetting the value. A gifted property keeps the donor’s original cost basis, which could result in massive taxes if you sell.

How long does probate usually take?

Timelines vary significantly to sell inherited house. It can take anywhere from six months to over two years depending on the state and the complexity of the estate.

Can one heir buy out the others?

Yes, this is very common. One sibling can buy out the others’ shares. You need to agree on a fair price for the home and then obtain financing to buy out the other shares.

What is a date-of-death appraisal and do I need one?

This is a property valuation as of the date the owner passed away. You should get one, as it establishes the stepped-up basis and protects you in an IRS audit. This is an important step to sell inherited house properly.

How Does Bail Bond Work? A Simple Step-by-Step Guide

How a bail bond works step by step

Getting that call that someone you care about is in jail is terrifying. Your mind races. You want to help. But you have no idea what to do or where to start. This is exactly when you start asking: how does a bail bond work? Understanding the process can save you time, money, and a whole lot of stress.

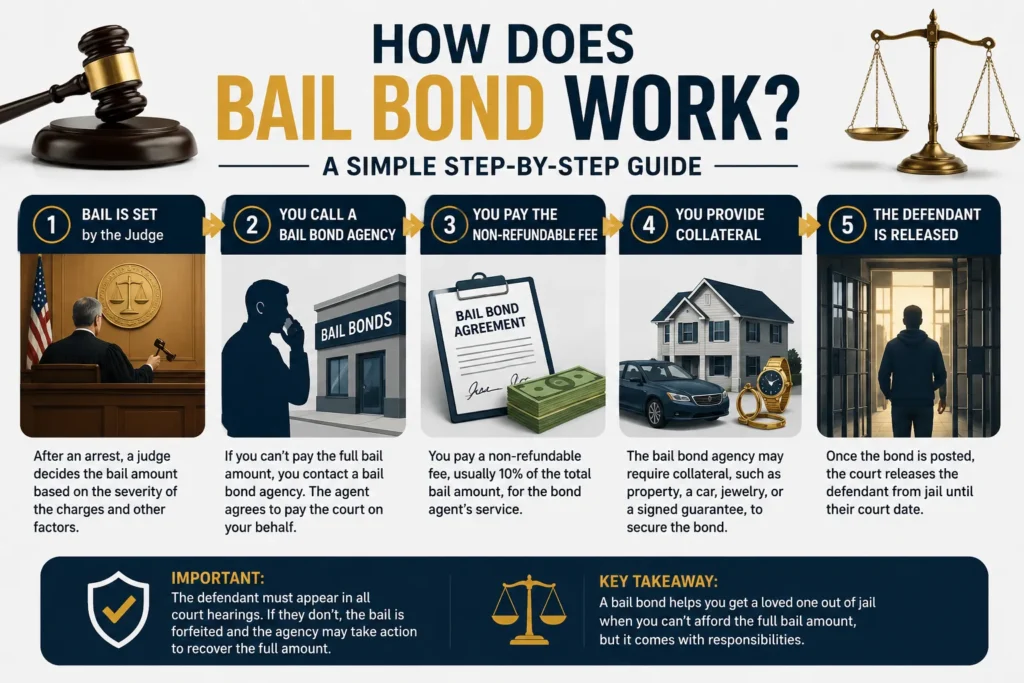
Step 1: Bail Is Set by the Judge

Here is where it all begins. After an arrest, a judge decides whether to let the person out before trial. If the judge thinks the person is safe and likely to show up for court, they set a dollar amount. This is called bail .

This amount is basically a promise. You pay the court, and you get it back if you show up to all your hearings.

But here is the problem you are looking to find: how does a bail bond work?  Most people cannot afford to pay thousands of dollars upfront. That is where bail bonds come in.

Step 2: You Call a Bail Bond Agency

If you cannot pay the full bail amount, you call a bail bond agency. The bail bond agent acts as a surety. They promise to pay the court the full bail amount if the defendant does not show up. This is how a bail bond services company helps someone get out of jail when they do not have the full bail money.

Step 3: You Pay the Non-Refundable Fee

Here is the cost. Most bail bond agencies charge a premium. This is a percentage of the total bail amount. The standard fee is usually 10% of the bail . For a $10,000 bail, you pay $1,000. Important: This fee is non-refundable. It is what the bond agent charges for taking the risk. You do not get this back, even if the defendant shows up to every court date.

Step 4: You Provide Collateral

Here is a big one. Bail bond agencies usually require collateral. This is something valuable to secure the bond in case the defendant runs . It could be property, jewelry, a car, or a signed guarantee from someone creditworthy. The bail bond collateral protects the agency. If the defendant skips court, the agency can seize the collateral to cover their losses.

Step 5: The Defendant Is Released

Once the fee is paid and collateral is secured, the agent posts the full bond amount to the court. The court releases the defendant from jail. They are free until their court date. But remember, this freedom comes with a responsibility. The defendant must show up to every court appearance. That is the law.

Bail bond process infographic

What Happens If the Defendant Misses Court?

This is where things get serious. If the defendant does not show up, the court forfeits the full bail amount . The judge issues a warrant for “jumping bail”. Now the bail bond agency is on the hook for the full amount . They will do whatever it takes to get that money back.

They may hire a bounty hunter to find the defendant . The bail agent is also authorized to arrest the defendant and bring them back to court. This is the main risk of the bail bond process. It is why agencies are so strict about collateral.

How Does a Bail Bond Work in Emergency Situations?

Here’s the thing about emergencies, they never happen when it’s convenient. You get that call at 2 AM, you’re half-asleep, and suddenly you gotta figure out how bail bonds work while your brain’s still catching up.

Good news? The process is the same whether it’s 2 PM or 2 AM. But knowing the steps before you’re in the middle of it? That saves you from making costly mistakes when you’re stressed and emotional.

What the bail bond agency needs from you:

– The defendant’s full name

– Their date of birth

– Which jail they’re at

They’ll run a quick background check to see if there’s any risk. If everything looks good, you pay the fee (that part’s non-refundable), put up some collateral, and the agent posts the bond. The whole thing can take just a few hours.

But here’s what most people don’t realize:

Understanding how bail bonds work before you actually need one gives you a huge advantage. You know what’s coming. You know what paperwork to grab. You know what questions to ask.

You’re not just panicking and making rushed decisions. You’re making smart calls because you already get how the process works.

That’s why taking five minutes to learn about bail bonds now could save you hours of confusion, thousands of dollars in mistakes, and a whole lot of stress when it really counts.

Conclusion: 

How does a bail bond work in simple terms? It is a loan. You pay a fee to a bail bond agency. The agency posts the full bail amount to the court. The defendant gets out of jail.

It is a simple process, but it is full of rules, risks, and non-refundable fees. Understanding the steps and requirements helps you make smart choices when it matters most.

Frequently Asked Questions

How much is the bail bond fee?

The fee is typically 10% of the total bail amount . Some states allow up to 15% for federal charges . This fee is non-refundable.

What are the bail bond requirements?

You usually need to pay the fee and provide collateral . The agency will also check the defendant’s background and community ties to assess risk.

What types of bail bonds are there?

There are different types of bail bonds. The most common is the surety bond through a bail bond agency. There are also cash bonds, property bonds, and personal recognizance bonds.

Do I get my bail bond fee back?

No. The fee is the bond agent’s compensation for their service. It is non-refundable, regardless of the outcome of the case.

What happens to my collateral?

You get your collateral back once the case is over and the defendant has appeared at all required court dates. If the defendant fails to appear, the agency keeps the collateral to cover their loss.

How does a bail bond work for a federal case?

Federal cases typically charge a 15% fee instead of the 10% standard for state charges. The process is the same, but federal rules and procedures apply.

Can I get a bail bond without collateral?

Sometimes. If the defendant is considered a very low risk, the bond agency might approve without collateral. However, this is rare. Most agencies require something to secure the bond.

What Is Loan-to-Value (LTV) Ratio? How It Works for Home Buyers

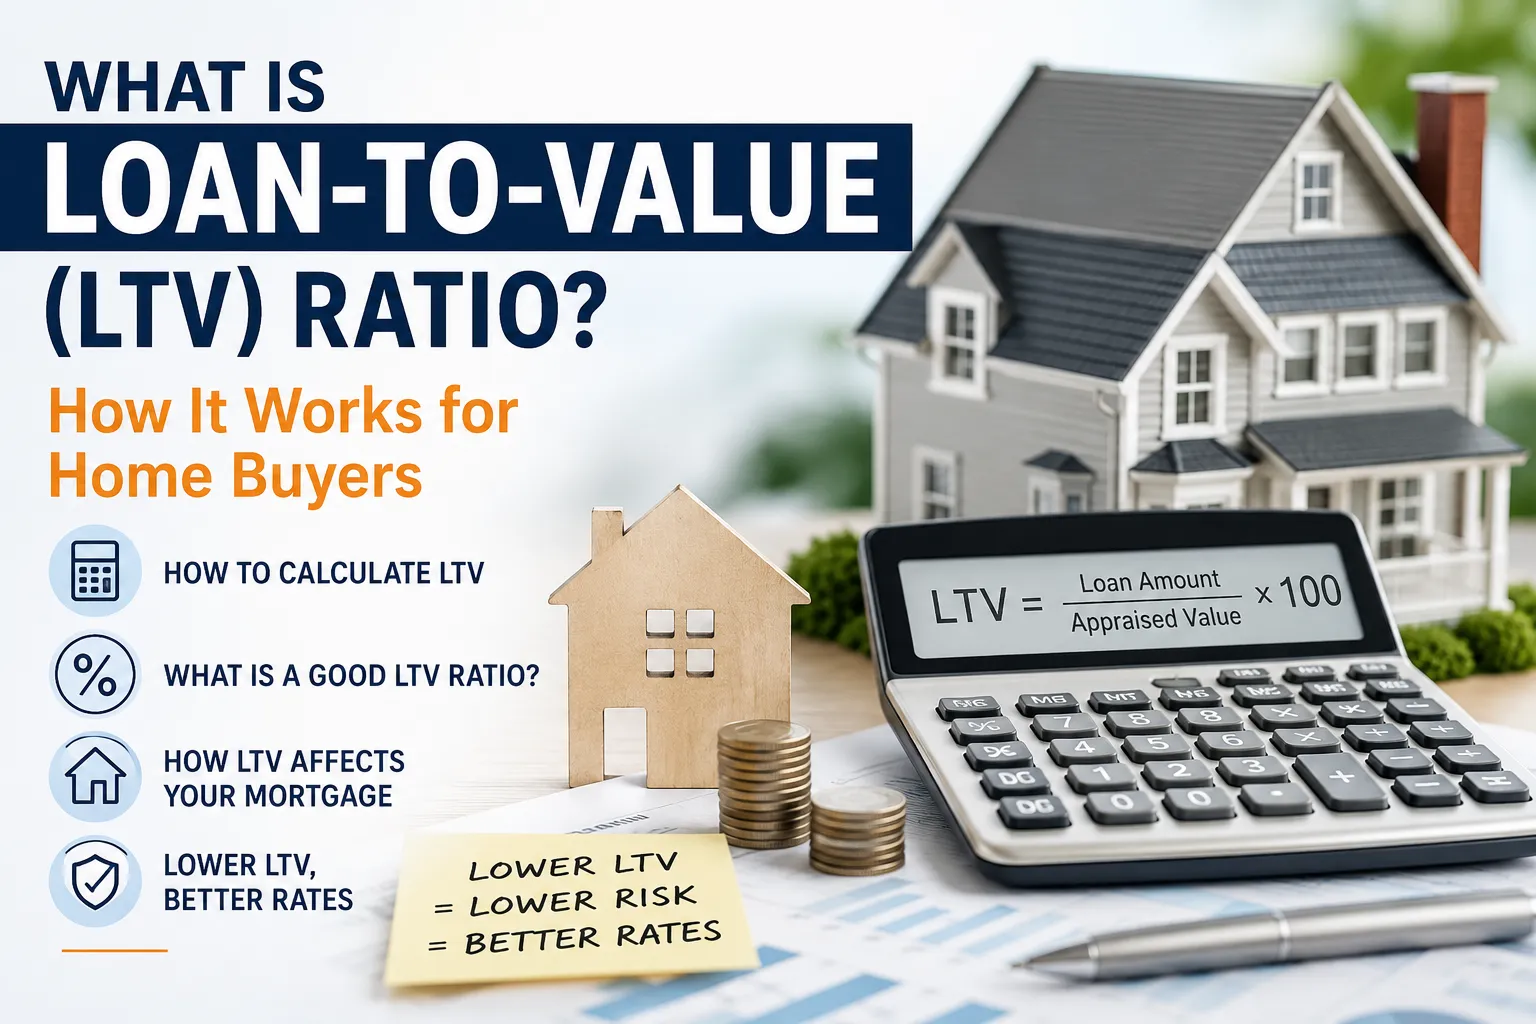
What is Loan-to-Value (LTV) Ratio? Illustration showing how LTV affects mortgage approval, home financing, PMI, and interest rates for home buyers.

Nobody plans to get denied for a loan. Or pay PMI for years. Or walk away from a deal because the appraisal came in low. But every home buyer faces these risks. And when they do, understanding what is loan to value ratio on a mortgage is what keeps the purchase on track. The question is, do you know how it works?

What is LTV in Home Loan?

What is loan to value ratio is a common question. Here is the simple answer. It is the amount you are borrowing divided by what the home is worth. Borrow $200,000 on a $250,000 house? Your LTV is 80%. That is it.

Lenders look at this number to size up their risk. Put more of your own money in and they relax. Borrow almost everything and they get nervous. That is why your LTV affects your interest rate, your monthly payment, and whether you have to pay PMI.

How to Calculate LTV (It Is Easy)

The math is simple for what is loan to value ratio.

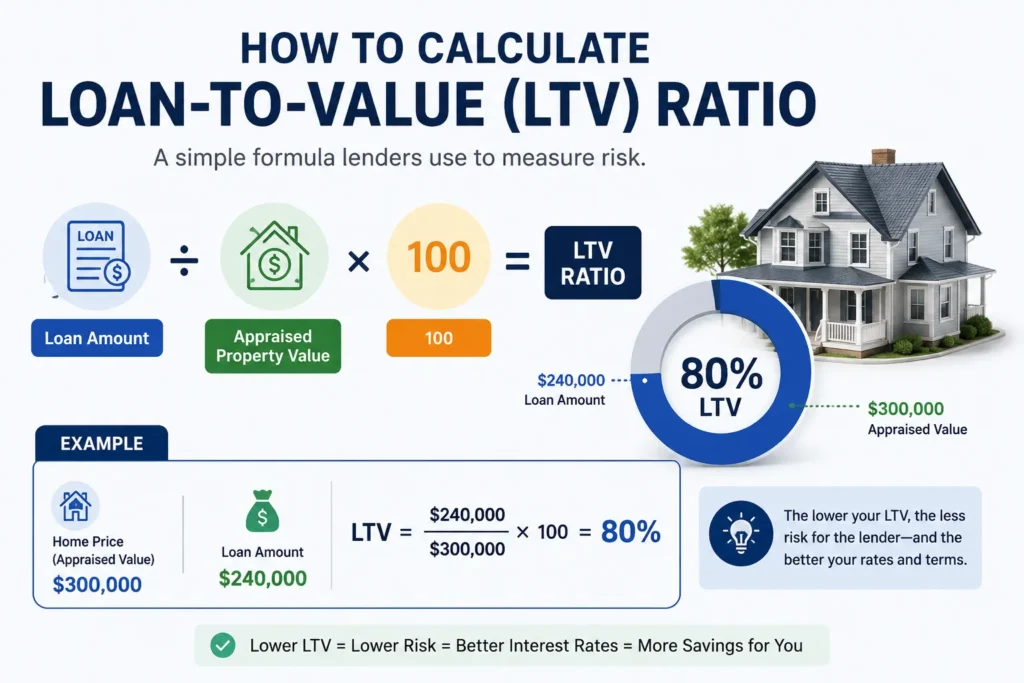
LTV = (Loan Amount ÷ Appraised Property Value) × 100

You can plug numbers into a loan to value ratio calculator and get the answer in seconds. But doing it by hand is just as fast. Here is a loan to value ratio example: you buy a home for $300,000 with a $270,000 loan. Divide 270,000 by 300,000 and multiply by 100. That gives you 90%.

One catch. Lenders always use the lesser of the purchase price or the appraised value. If the house appraises low, your LTV goes up. That is why a low appraisal can kill a deal or force you to bring more cash to the closing table.

Why LTV Matters So Much

The loan to value ratio on a mortgage affects three big things.

  • Your interest rate: Lower LTV means lower rates. A one percentage point difference can cost you thousands over the life of the loan.
  • Private mortgage insurance: LTV above 80%? You pay PMI. That is extra money every month until you build enough equity to get rid of it.
  • Getting approved: Some loans have max LTV limits. Conventional loans allow up to 97% with 3% down. VA and USDA loans allow 100% with zero down.

What is a Good Loan to Value Ratio

A good loan to value ratio is 80% or less. That means you put 20% down and skip PMI altogether. A loan to value ratio between 60% and 75% is even better and often unlocks the lowest rates.

Government loans are more forgiving. FHA allows 96.5% LTV with 3.5% down. VA allows 100% with nothing down at all.

Infographic explaining how to calculate the Loan-to-Value (LTV) ratio using the loan amount and appraised property value with a real mortgage example.

What Does LTV Mean in Loans

What does ltv mean in loans gets asked all the time. It tells the lender how much of the property you are financing. The higher the percentage, the more you are borrowing and the less equity you have.

What is ltv in mortgage loan terms? It is a risk gauge. A low LTV gives the lender a cushion if you default. A high LTV means you have less to lose, which makes you more likely to walk away.

Combined LTV: The Second Loan Catch

If you have a second mortgage or a HELOC, lenders look at combined LTV or CLTV. That is your first mortgage plus any other loans against the property.

Example: first mortgage $250,000, HELOC $50,000, home worth $300,000. Your CLTV is 100%. Most lenders want CLTV below 85% to 90%. Go over that and you face higher rates or outright denial.

How LTV Affects Refinancing

Refinancing is just like buying when it comes to LTV. To refinance a conventional loan without PMI, your LTV usually needs to be 80% or lower.

Above 80%? You might still qualify through FHA, VA, or certain conventional programs. But you will pay higher rates and mortgage insurance.

How to Lower Your LTV

  • Put more money down. This is the most direct way.
  • Buy a cheaper house.  Smaller loan means lower LTV.
  • Wait for your home to go up in value. Market appreciation helps over time.
  • Pay extra on your principal.  Every extra dollar lowers your loan balance and improves your LTV.
  • Make improvements that add value. Remodels that boost appraisal value can lower LTV at refinance time.

LTV and Your Monthly Budget

A lower LTV saves you more than just PMI. It can shave hundreds off your monthly payment. That is money you can put toward other things.

Home buyers get fixated on the down payment, but LTV is the bigger picture. A larger down payment lowers your loan, improves your LTV, and saves you money for years to come.

Conclusion: 

What is loan to value ratio? It is the percentage of the home’s value that you are financing. A lower LTV means less risk for the lender, which means better rates, lower payments, and no PMI for you. A good LTV keeps more money in your pocket over the life of the loan.

Frequently Asked Questions

What is loan to value ratio?

It is your loan amount divided by the home’s value. Borrow $200,000 on a $300,000 home and your LTV is 67%. The lower the number, the better off you are.

What is a good loan to value ratio for a mortgage?

A good loan to value ratio is 80% or below. That means you have 20% equity and can avoid PMI. An LTV between 60% and 75% usually gets the best interest rates.

What is the maximum LTV for a conventional loan?

Conventional loans go up to 97% LTV with 3% down for qualified buyers. FHA allows 96.5% with 3.5% down. VA and USDA allow 100% with no down payment.

How can I lower my loan to value ratio?

Make a bigger down payment, buy a cheaper home, wait for the home to appreciate, pay down your principal faster, or make improvements that boost the home’s value.

Why does LTV matter for mortgage rates?

Lenders see lower LTVs as less risky. Borrowers with lower LTVs get lower rates. A one-point difference can save you thousands over the life of the loan.

What is combined loan-to-value ratio?

Combined LTV or CLTV includes all loans on the property, like a first mortgage and a HELOC. Lenders use it to assess overall risk when you have multiple loans.

Does a lower LTV always mean a lower rate?

Generally yes. Borrowers with LTVs of 80% or less get better rates. Higher LTVs mean higher rates and mortgage insurance.

Can I refinance with a high LTV?

Yes. FHA and VA programs allow high LTV refinancing. Some conventional programs do too, but with higher rates and insurance costs.

What is LTV in home loan terms?

It is the lender’s risk meter. High LTV means less equity and more risk for the lender. Low LTV means more cushion and less risk.

What does LTV mean in loans overall?

What does ltv mean in loans? It is the loan amount divided by the collateral value. For mortgages, that is the home’s purchase price or appraised value. It is the main risk measure in real estate lending.

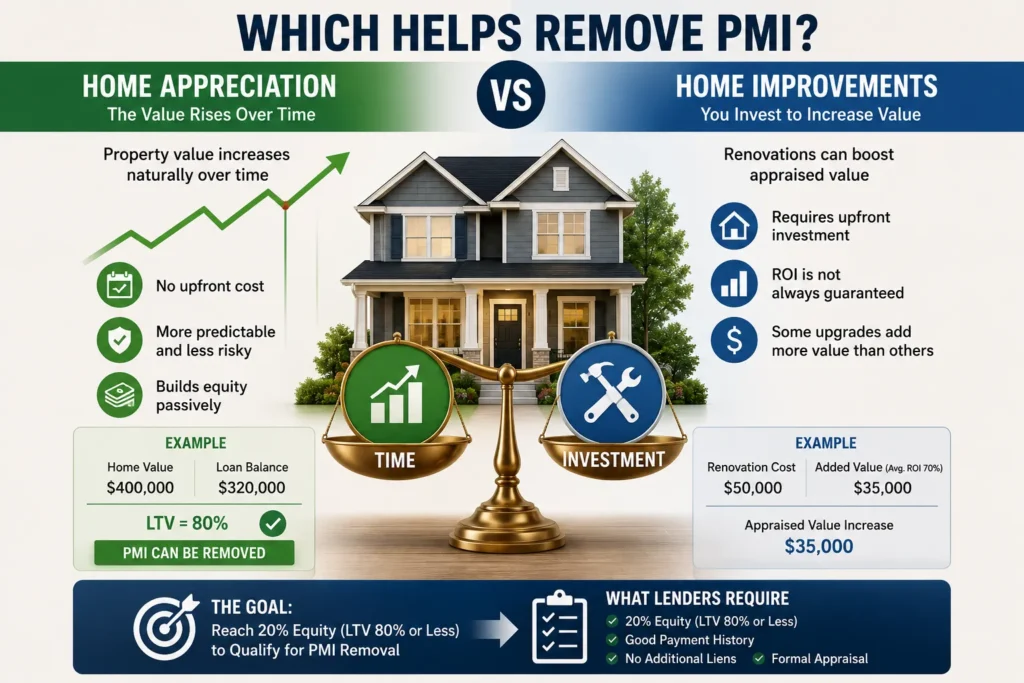
Home Appreciation vs Home Improvements: Which Helps Remove PMI?

Comparison of home appreciation and home improvements showing how each can increase home equity and help remove PMI.

You are paying Private Mortgage Insurance removal every month. You are eager to get rid of it. This is understandable. PMI is an extra fee for conventional mortgage borrowers who put down less than 20 percent. It can add $30 to $70 per month for every $100,000 borrowed.

That feels like money going nowhere. So you start looking for a faster way out. You hear about two different strategies: riding the wave of house appreciation, or spending money on home improvements to increase your home’s value.

The question is, which one actually helps you Remove PMI?

The Core Difference: Which Strategy Is More Certain?

Here is the reality check. Renovating to boost your home’s value sounds like a smart way to drop PMI, but appraisals aren’t guaranteed to come in high enough. On average, homeowners get back about 70% of what they spend on renovations, according to RenoFi. This means a $50,000 renovation could raise a home’s value by just $35,000.

If you are spending money to save money, the math must work in your favor. Relying on a renovation to boost your value enough to reach the 20% equity threshold is risky. The appraisal must be high enough, and renovations rarely add more value than they cost.

Paying down your mortgage principal may be a more reliable way to increase equity enough for Home appraisal for PMI removal. Every extra dollar you pay goes directly toward your principal balance and increases your home equity dollar for dollar.

How to Remove PMI: The Two Main Routes

Here is how both strategies work in practice.

Route 1: Home Appreciation (and Paying Down Your Loan)

You can request to cancel PMI when you reach 20% equity in your home. Your loan-to-value ratio (LTV) is the amount you owe on your mortgage compared to the home’s value. You can reach this 20% equity threshold in a few ways.

Make extra payments. This is the most reliable method. Anything above your lender-required payment goes directly toward your principal balance. If you owe $300,000 on a $360,000 home, your LTV is 83%. You are not yet at 80%. If you pay an extra $10,000 toward your principal, your loan balance drops to $290,000. Your LTV is now 80.5%, still slightly above 80%. Getting to an LTV of 80% or less qualifies you to request PMI removal.

If your home value increases due to fair market value, your LTV drops. For example, if your home appraises for $375,000, and you owe $300,000, your LTV is exactly 80%. You now qualify to ask your lender to remove PMI.

Request a new appraisal. If you believe your home has increased in value, you can order a new appraisal. Rising home values can build equity and increase your stake in the property. You will need to prove this to your lender with an official valuation.

Route 2: Home Improvements

You can also use home improvements to increase your home’s appraised value. If your home’s appraised value goes up, your equity goes up too. And that can get you to that 20% LTV mark way faster.

But you gotta pay attention to the return on investment. A full kitchen remodel? You might get back about 96% of what you spent. But a super high-end one? That could drop to around 49.5%. Big difference. Adding a bedroom, especially a big one with a bathroom, can bump your home’s value by up to 24%, particularly if you’re going from three bedrooms to four.

Now, fresh paint or new appliances? Don’t expect much. Appraisers don’t really care about that stuff. They look at structural improvements – think kitchen remodels, bathroom upgrades, extra square footage, or structural changes. And they compare your home to similar ones in the area. Then they factor in the big stuff. That’s what really moves the needle.

Infographic comparing home appreciation and home improvements to explain PMI removal, home equity, and loan-to-value ratio.

What You Need to Request PMI Removal

To request early PMI cancellation, you must meet specific requirements. Most lenders require enough home equity, a strong payment history, and proof that there are no additional liens against the property.

  • Acceptable payment record: No payments 30 or more days past due in the last 12 months; no payments 60 or more days past due in the last 24 months.
  • No second liens: You may need to certify that there are no second mortgages or HELOCs attached to the property.
  • Seasoning requirements: Some lenders require you to wait a minimum amount of time before requesting PMI cancellation.
  • Written request: You need to submit a formal letter to your lender.

If your mortgage is a conventional loan, you can usually request PMI removal once you reach 20% equity. Under federal law, PMI is generally removed automatically when the loan balance reaches 78% of the home’s original value if you are current on payments.

Conclusion

Home improvements are not an automatic ticket to removing PMI. The appraisal is not guaranteed, and renovations rarely pay for themselves dollar-for-dollar. They can help, but they are a gamble.

Home appreciation combined with paying down your principal is the more reliable path. Every extra dollar you pay toward your principal is a guaranteed step toward 20% equity. If your home values rise naturally due to market conditions, you can request a new appraisal and remove PMI without spending a dime on renovations.

If you are early in the buying process, the most reliable way to avoid this dilemma is to delay your home purchase and save enough for a 20% down payment to avoid PMI altogether.

Frequently Asked Questions

Can I cancel PMI if my home value increases?

Yeah, you can. If your home’s value goes up enough to bring your loan-to-value ratio down to 80% or less, you can ask to cancel PMI. You’ll need a new appraisal and proof that you’ve been making your payments on time.

Is it better to make extra mortgage payments or renovate to remove PMI?

Paying extra toward your principal is the safer bet. It builds equity dollar for dollar. Renovations? They’re a gamble. No guarantee they’ll boost your value enough to cover what you spent. So stick with extra payments if you want certainty.

What renovations help with PMI removal?

Ones that add real square footage or usable space like finishing a basement or converting an attic. Those can actually bump up your appraisal. Cosmetic stuff like paint or new countertops? Barely moves the needle.

How long does PMI removal take after requesting it?

Usually a few weeks. They’ll check your equity, review your payment history, and sometimes order a new appraisal. Just gotta be patient.

Can refinancing remove PMI?

Yes. If you refinance and your new loan is 80% or less of your home’s value, PMI goes away. Works great if your property value has gone up.

What is the minimum equity percentage needed to request PMI removal?

You need at least 20% equity, so your loan-to-value ratio is 80% or less. Some lenders let you cancel at 80%, others make you wait till 75% for early removal.

How much does a new appraisal cost for PMI removal?

Usually between $300 and $600. Depends on where you live and the size of your property.
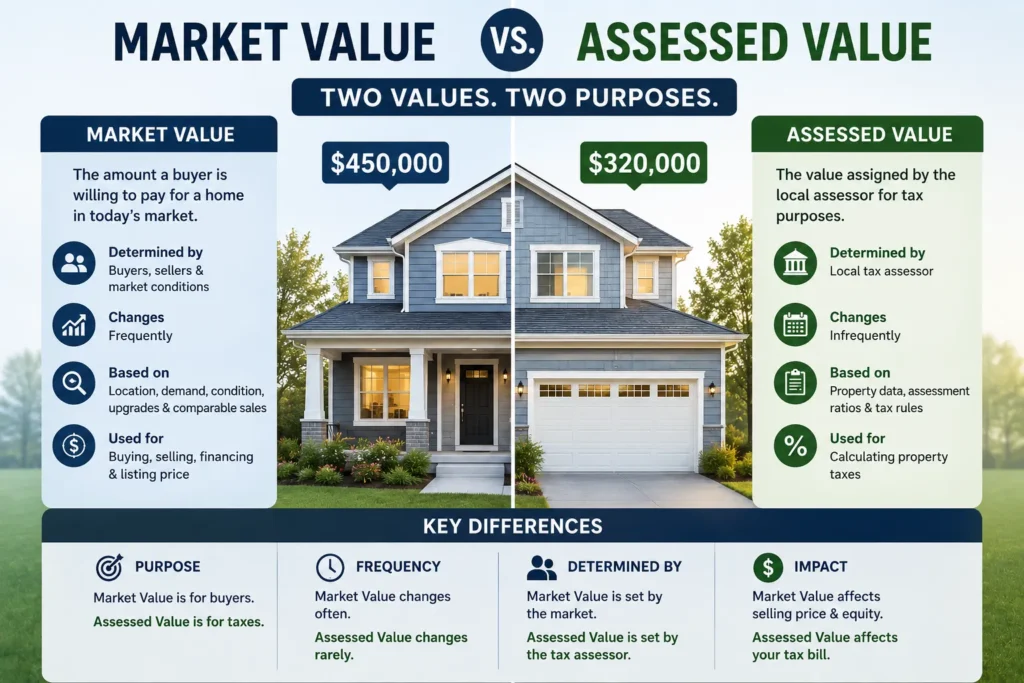
Can I use an online estimate instead of an appraisal to prove my home’s value?

Nope. Lenders won’t accept that. They need a formal appraisal or a broker price opinion.

Does my mortgage type affect how I can remove PMI?

Yes. Conventional loans let you cancel once you hit 20% equity. Different loan types have different rules.

What happens if my PMI removal request is denied?

They have to tell you why in writing. Usually it’s because you don’t have enough equity, missed payments, or the appraisal came in low.

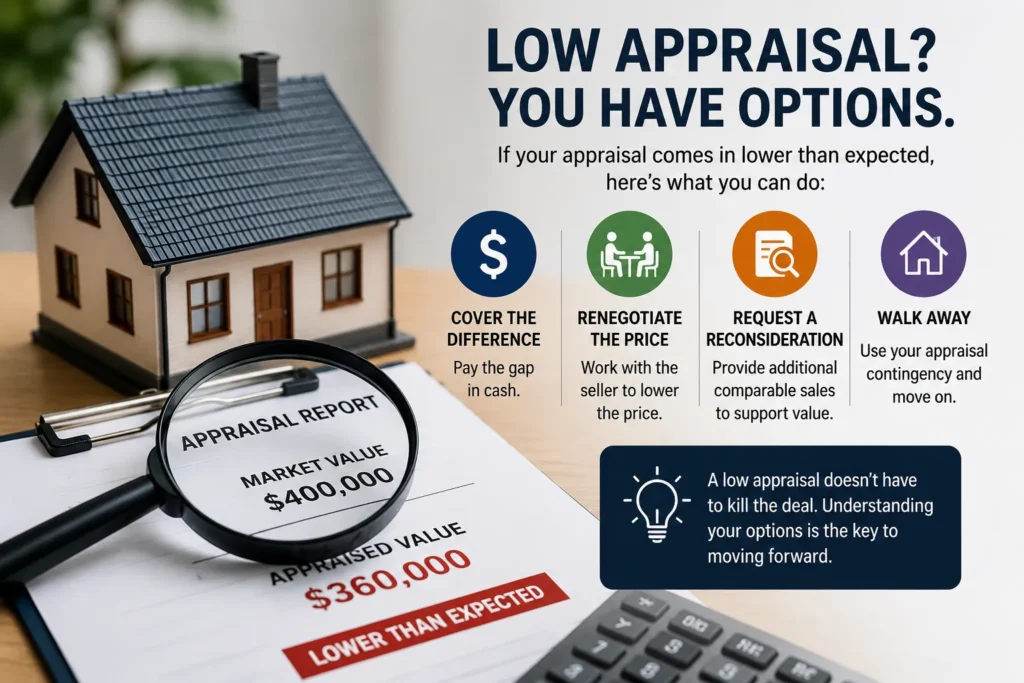
What Happens If Your Appraisal Comes in Lower Than Expected?

Home appraisal came in low showing a house, appraisal report, and lower appraised value during a real estate transaction.

You found the perfect home. Made an offer. Got accepted. Then the appraisal refinance comes back low. It is frustrating. It is stressful. But here is the thing. A low home appraisal is not the end of the road. It is a bump, not a dead end.

This guide covers what happens when an appraisal falls short and what to do next, and home appraisal tips. Whether buying or refinancing, the options are clearer than most people think.

What a Low Appraisal Actually Means

An  appraisal refinance is a licensed opinion of what a home is worth. Lenders order them because the property is collateral. If a buyer stops paying, the lender needs to sell that home to recover money.

A low appraisal simply means the appraised value came in below the purchase price for a buyer. Or below what was needed to support the requested loan amount for a refinance borrower.

Most lenders calculate loan-to-value using the lower of the contract price or the appraised value. That means a $400,000 contract on a home that appraises for $385,000 will be treated as if the home is worth $385,000.

The math then gets tricky. With a 20% down payment, the buyer’s required cash to close was $80,000. Now the lender will only lend $308,000 (80% of $385,000) instead of $320,000. The buyer either makes up the $12,000 gap, restructures the deal, or walks away.

Why Appraisals Come in Low

Several factors can cause an appraisal lower than purchase price to miss the mark.

Inadequate comparable sales are a big one. Appraisers need three or more closed sales of truly similar properties within the last six months. Custom homes, rural properties, and homes in transitional neighborhoods are especially at risk.

Hot markets and bidding wars also cause gaps. Appraisers rely on closed deals, not active bidding. If prices are rising fast, recent sales data may not reflect current market demand. About 8% of appraisals come in below the contract price.

Property condition matters too. A roof nearing the end of its life, a wet basement, or deferred maintenance can pull down value. Government-backed loans like FHA and VA have minimum property requirements that can flag needed repairs.

Sometimes appraisers simply make mistakes. Wrong square footage, incorrect bedroom counts, or missed upgrades can lead to a low number.

What Happens During an Appraisal Refinance 

For  appraisal refinance, a low appraisal affects the loan-to-value ratio (LTV). LTV is the loan amount divided by the home’s appraised value. A lower value means a higher LTV, which can mean higher rates or mortgage insurance.

If the LTV goes above 80%, private mortgage insurance may be required. Above 97%, the loan might be considered underwater, and lenders may not refinance at all .

There are ways around this. Fannie Mae and Freddie Mac offer high LTV refinance programs for certain borrowers. Some streamline refinance programs skip appraisals entirely for government-backed loans.

New rules starting in 2025 allow more borrowers to skip appraisals entirely. Appraisal waivers and alternatives have saved borrowers over $4.1 billion in fees since early 2020.

Illustration showing options after a low home appraisal, including paying the appraisal gap, negotiating with the seller, requesting a reconsideration of value, or walking away.

What Homebuyers Can Do When an Appraisal Comes in Low

  • Cover the difference in cash:  If the buyer has extra money, they can pay the gap out of pocket. This is common in competitive markets.
  • Renegotiate the purchase price: Ask the seller to lower the price to match the appraised value. Many sellers agree rather than risk losing the deal.
  • Request a reconsideration of value:  This is a formal request asking the appraiser to review their decision with new information. The ROV process is now standardized across Fannie Mae, Freddie Mac, FHA, and VA loans. To make an ROV work, provide up to five additional comparable sales. These should be closed sales within the last six months, within a mile, and similar in size, age, and condition.
  • Walk away:  If there is an appraisal contingency in the contract, the buyer can cancel without losing earnest money. About 52% of buyers include appraisal contingencies in their offers.

What Sellers Can Do When an Appraisal Comes in Low

Lower the price. Agreeing to the  appraisal refinance value keeps the deal moving. It reduces profit but avoids relisting. Instead of dropping the price, offer to cover closing costs or split the difference of  appraisal refinance. 

Request a reconsideration of value. Sellers can also support an ROV if they believe the appraiser missed key details. If no agreement is reached, sellers can walk away and try again. This carries risks but sometimes works.

Refinance Appraisal Gap Coverage

An appraisal refinance gap clause states that the buyer will cover some or all of the difference if the appraisal comes in low.

For example, offering $400,000 with $20,000 gap coverage means the buyer will pay up to $20,000 above the appraised value. This reassures sellers the deal will close .

Gap coverage can make offers stronger in competitive markets. But it also increases risk. Buyers need cash beyond their down payment and closing costs.

Conclusion

An appraisal refinance and low appraisal is stressful but solvable. Buyers can pay the gap, renegotiate, dispute the appraisal, or walk away. Sellers can lower the price, offer concessions, or relist.

For  appraisal refinance, a low appraisal affects LTV and may trigger mortgage insurance. But programs exist to help, and appraisal waivers are more common than ever.

Understanding the options makes the process less intimidating. The deal is not dead. It just needs a different path forward.

Frequently Asked Questions

What happens if appraisal is lower than offer?

The lender will only loan based on the appraised value, not the contract price. The buyer must cover the difference, renegotiate with the seller, or walk away under an appraisal contingency.

How often do appraisals come in low?

Industry estimates suggest fewer than 10% of appraisal to refinance come in below the contract price. But the risk increases in hot or volatile markets.

Can you challenge a low appraisal?

Yes. Request a reconsideration of value by submitting stronger comparable sales or pointing out factual errors in the report. This is now standardized across major loan programs.

What is appraisal gap coverage?

A contract clause stating the buyer will cover some or all of the difference if the home appraises below the offer price. It strengthens offers in competitive markets but adds cash requirements.

Do sellers have to lower the price after a low appraisal?

No, but they may need to negotiate if they want to keep the deal alive. Sellers can refuse and relist, though that carries risks .

What happens if an appraisal is low on a refinance?

It raises the LTV ratio, potentially triggering mortgage insurance, higher rates, or loan denial. Options include paying mortgage insurance, a cash-in refinance, or using a high LTV program.

Can you switch lenders after a low appraisal?

Yes, but expect a new appraisal and additional costs. Different lenders may use different appraisal management companies, potentially yielding a different result.

How long does it take to challenge a low appraisal?

Most disputes are settled in one to three weeks. Speed depends on documentation and responsiveness of the appraiser and lender.

What is an appraisal contingency?

A clause in the purchase contract allowing the buyer to cancel without penalty if the appraisal refinance appraisal comes in low. About half of buyers include this protection.

Who pays for an appraisal gap?

The buyer typically pays the gap since lenders won’t finance above the appraised value. Sellers sometimes agree to concessions or price reductions to help.

Market Value vs Assessed Value: What’s the Difference?

market value vs assessed value of a home, showing how market price differs from property tax assessment.

The conversation usually starts the same way. A homeowner opens the property tax bill. Looks at the number. Then a real estate website opens. Look at another number. And suddenly the question comes out. How can the same house have two different values?

The house did not change overnight. Nobody added another bedroom. Nobody built a second floor. So why are the numbers different?

The answer is actually very simple.

  • One value is there for taxes.
  • One value is there for the real estate market.

That is why understanding assessed value vs market value matters. These two numbers belong to the same home, but they are trying to answer two completely different questions.

Think of it like this. One person is asking: How much tax should this house pay? Another person is asking: How much would somebody buy this house for today?

Those answers are rarely exactly the same.

And that is perfectly normal.

What is Assessed Value?

Many homeowners search what is assessed value after seeing the number on their tax statement. The easiest explanation is this. The government needs a number to calculate taxes. That number is called assessed value. The local assessor reviews property information and assigns a value.

The assessed value of property helps determine:

  • Property taxes
  • School taxes
  • County taxes
  • Local government taxes

The tax office is not trying to guess what buyers will offer next week.

Their job is simply determining taxable value. That is why the Property Assessed Value may stay the same even while home prices rise.

Think About Your Car for a Minute

A car dealership may offer one price. An insurance company may use another value. A private buyer may offer something completely different. The car itself has not changed. The purpose of the value changed.

Homes work the same way. The tax office sees one value. The market sees another. This is the heart of assessed value vs market value.

What is Market Value?

Now imagine putting a For Sale sign in front of the house. People start scheduling showings. Buyers walk through the rooms. Agents discuss pricing. Offers begin arriving.

  • One buyer offers $390,000.
  • Another offers $405,000.
  • Someone offers $420,000.

The number buyers are willing to pay becomes the market value. That value changes because of:

  • Location
  • Demand
  • Interest rates
  • Home condition
  • School districts
  • Upgrades
  • Local market conditions

Unlike tax values, market values move constantly. That is another reason assessed value vs market value often shows different numbers.

Comparison chart explaining the differences between market value and assessed value, including purpose, calculation, and impact on property taxes

Assessed Value vs Market Value: The Kitchen Table Explanation

Imagine sitting at the kitchen table with a friend. The friend asks: What is your house worth? The answer depends on the question. If the friend asks: How much are your property taxes based on? The assessed value matters.

If the friend asks: How much could you sell it for? The market value matters. Sometimes people make this much more complicated than it really is. The truth is simple.

One number belongs to the tax office.

One number belongs to buyers.

QuestionAssessed ValueMarket Value
Used for taxesYesNo
Used for sellingNoYes
Changes quicklyUsually noOften
Determined byTax assessorBuyers and market
Used by lendersRarelyYes

Why is Assessed Value Usually Lower?

This is probably the biggest question homeowners ask. My house could sell for $500,000. So why does my tax bill say $350,000? Several things happen.

The housing market moves fast. The tax office moves slowly. Home prices can rise in a few months. Assessments may happen every few years.

Some states limit how much assessments can increase. Some improvements are not immediately recorded. Because of these reasons, assessed value vs market value often creates a large gap.

How is Market Value Determined?

Many sellers ask How Is Market Value Determined before listing their homes.

Imagine two houses. Same neighborhood. Same size. Same number of bedrooms. One has a remodeled kitchen. One needs repairs. The updated house usually sells for more. Market value comes from things buyers care about.

Recent Sales

What nearby homes sold for.

Condition

How well the property has been maintained.

Location

The neighborhood often matters as much as the house itself.

Demand

More buyers usually mean higher prices.

Appraisals

Professional opinions also help establish value.

This is why assessed value vs market value can never always match perfectly.

How is Assessed Value Calculated?

Many homeowners ask How Is Assessed Value Calculated after receiving their assessment notice.

The tax office may review:

  • Property size
  • Lot size
  • Home age
  • Building characteristics
  • Local market data
  • Assessment ratios

For example:

ItemAmount
Market Value$400,000
Assessment Rate80%
Assessed Value$320,000

That amount becomes the Property Assessed Value.

Understanding Property Tax Assessment

A Property Tax Assessment affects annual tax bills. Think of it this way. Higher assessment. Higher taxes. Lower assessment. Lower taxes. The calculation usually looks like this:

Property tax = Assessed value × Tax rate

That is why homeowners watch assessments carefully. Even small changes can affect yearly expenses.

Does Assessed Value Decide the Selling Price?

Not really.

Imagine a homeowner saying:

The county says my house is worth $280,000, so that is my asking price. Meanwhile, every home nearby sells for $375,000. The market does not care what the tax bill says.

Buyers care about:

  • Location
  • Updates
  • Layout
  • Neighborhood
  • Schools
  • Competition

The Assessed Value of a Home rarely determines the final selling price.

Home Value Assessment Methods

A Home Value Assessment can come from several places. A real estate agent may give one value. An appraiser may give another. An online estimator may show something different.

The tax office may have another number. This often confuses homeowners. But every value serves a different purpose.

Can the Assessed Value Be Wrong?

Absolutely. Mistakes happen. The county may list the wrong square footage. The number of bathrooms may be incorrect. An unfinished basement may be listed as finished. A homeowner may discover errors only after reviewing records. Understanding assessed value vs market value helps identify these issues.

When Home Prices Rise Fast

Picture a neighborhood becoming extremely popular. Homes sell in three days. Buyers compete. Prices increase every month. Yet the tax records still show values from several years ago. The gap grows wider. This is often when homeowners first realize that market value and assessed value are not the same thing.

Which Number Should Matter Most?

That depends on the situation. Selling the home? Market value. Buying the home? Market value. Paying taxes? Assessed value. Appealing taxes?

Both values. Refinancing? Market value. Building equity? Market value.

Every number has a purpose. The key is understanding when each one matters.

Conclusion:

The confusion usually starts with two numbers. One house. Two values. At first it feels wrong. But it really is not. The tax office is asking one question. The housing market is asking another.

One value determines taxes. One value determines the selling price. Neither number is incorrect.

They simply tell different stories about the same property.
And once homeowners understand assessed value vs market value, the numbers stop being confusing and start becoming useful.

Frequently Asked Questions

What is assessed value?

Assessed value is the amount assigned by local tax authorities to calculate property taxes and may not reflect what the home could sell for today.

Why is assessed value lower than market value?

Assessment schedules, local tax laws, and delayed updates often cause assessed values to remain below current market prices.

What determines market value?

Buyer demand, neighborhood conditions, home features, location, and recent sales all contribute to market value.

Does assessed value affect selling price?

Most buyers focus on market conditions and comparable sales rather than property tax assessments.

How often are homes reassessed?

Assessment schedules vary, with some areas reassessing annually and others updating values every few years.

Can renovations increase assessed value?

Major improvements may eventually increase assessed values during future reassessments.

Can homeowners appeal assessments?

Yes. Property owners can challenge assessments if they believe the value is inaccurate.

Why do online estimates differ?

Online estimates follow market conditions while tax assessments follow local government rules.

Which value matters for refinancing?

Lenders usually focus on market value because it reflects current property worth.

Why is understanding both values important?

Knowing both values helps homeowners understand taxes, equity, selling prices, refinancing options, and financial planning.

Home Appraisal Cost in 2026: Average Fees and What to Expect

home appraisal cost 2026 average fees

Home appraisal cost is one of those real estate things that sounds small at first, but the moment a property deal gets serious, it suddenly becomes a big part of the conversation. 

It is the money paid in 2026 to a licensed real estate appraiser who comes, looks at the home properly, studies the market, and tells what the property is actually worth.

And here is the real point people feel later on: Mortgage Appraisal Process is the step that decides how strong the property value looks in front of a bank or lender.

What does Home Appraisal Cost Really Mean?

It is basically paying someone who knows the market very well to walk through a property and say, in a professional way, “this is what this home is worth right now.”

Not emotional value. Not asking price. Just real market value.

So When Fair Market Value Appraisal is paid, it covers:

  • A full walk-through of the house
  • Checking condition, size, layout
  • Looking at nearby recent home sales
  • Understanding location demand
  • Writing a proper valuation report

In speaking tone, home cost is like paying for a reality check on property value.

Average Home Cost in 2026 (Real Simple Breakdown)

The Home Appraisal Chicago IL cost in 2026 depends on how simple or complex the property is.

Easy view:

Property typehome appraisal cost
Small home$350 – $500
Normal house$350 – $650
Condo$300 – $500
Large home$600 – $1,200
Luxury property$1,000 – $3,000+

So Property Appraisal Cost stays manageable for normal homes, but once the property gets bigger or more complex, the cost naturally goes up.

Why Home Appraisal Cost Changes From One Case to Another

Here is where people usually get confused about average appraisal cost.

It is not fixed because no two properties are the same, and no two locations behave the same.

Simple reasons:

  • Bigger homes take more time to check
  • Expensive areas need deeper market study
  • Rural areas have fewer comparison homes
  • Unique houses need more expert judgment
  • Fast appointments increase appraisal cost

So basically, appraisal cost moves with effort, time, and difficulty.

Home Cost in Mortgage Process (how it really feels)

When a Home Appraisal for Mortgage cost becomes a must-have step.

Here is how it usually goes:

  • Loan application is submitted
  • Bank orders appraisal
  • Appraiser visits the property
  • Market comparison is done
  • Final report goes to lender

And this is the moment that matters:
If average home appraisal cost leads to a lower value than expected, the bank may reduce the loan or ask to renegotiate the price.

So, it can directly change how the deal moves forward.

Fair Market Value and Appraisal Cost Connection

It is all about finding fair market value.

Fair market value simply means:

  • What a normal buyer would realistically pay
  • Based on current real sales in the area
  • Not inflated price
  • Not emotional pricing

So when appraisal cost is done, it gives a number that feels realistic and accepted by lenders.

Home Cost in Busy Markets like Chicago IL

In active cities like Chicago IL, appraisal cost feels a bit more detailed because everything moves faster.

Why it Feels More Complex:

  • Prices change quickly
  • Lots of condos and apartments
  • Different property types in one area
  • Strong buyer competition
  • Constant market movement

So appraisal cost in such places usually includes more comparison work and deeper analysis.

Property Condition and Appraisal Cost (Real-World View)

The condition of a home plays a quiet but important role in appraisal cost work.

Here is what actually happens:

  • Clean homes are easy to evaluate
  • Renovated homes are clearer in value
  • Damaged homes take extra checking
  • Unfinished areas need deeper review

So even if home cost is not charged based on condition directly, condition still affects how much work is needed.

Home Cost vs Online Estimates (big real difference)

A lot of people think online tools are similar to appraisal cost, but they are not.

Online Estimates:

  • Quick and automatic
  • Based on general data
  • No physical visit

Appraisal:

  • Real inspection
  • Market comparison
  • Professional judgment
  • Accepted by banks

So home appraisal cost is basically paying for accuracy, not guessing.

Simple Ways to Make Home Cost Process Easier

Even though the appraisal cost itself does not really change, the process can feel smoother.

Simple Actions:

  • Keep home clean and organized
  • Make upgrades easy to see
  • Keep repair or renovation records ready
  • Allow full access to property areas

These steps don’t reduce appraisal cost, but they make the whole process faster and smoother.

Conclusion:

At the end of the day, home appraisal cost is not just a fee on paper. It is the moment where a property gets its real financial identity.

It quietly decides how much a home is worth in the eyes of a bank, buyer, and market in 2026.

And that is why appraisal cost always stays an important step in every real estate deal.

Frequently Asked Questions

What is the appraisal cost in very simple speaking terms?

It is the fee paid to a licensed professional who visits a property, studies it carefully, compares it with similar homes, and gives an official market value report used by banks during mortgage approval in 2026.

Why does home cost feel different for every property?

It  feels different because every property has its own size, condition, location, and complexity, and these factors change how much time and effort the appraiser needs to complete an accurate valuation.

Who usually pays appraisal cost in real estate deals?

In most cases, the buyer pays the appraisal cost as part of closing expenses, although sometimes lenders or sellers may cover it depending on the negotiation and mortgage agreement.

What happens after appraisal cost report is completed?

After the appraisal cost report is completed, the lender reviews the property value to decide if the loan amount matches the home value or if changes are needed before final approval.

Can home appraisal cost be skipped during mortgage approval?

It usually cannot be skipped because lenders need a verified property value before approving any loan, making it a required step in almost all mortgage processes.

How long does appraisal cost process usually take?

The appraisal cost process usually takes a few days to a week depending on scheduling, property size, and how quickly market comparison data can be gathered and analyzed.

Does renovation affect home cost directly?

Renovation does not directly affect home appraisal cost, but it can change how much work is needed to evaluate the property and how clearly the final value can be determined.

Why is home appraisal cost important for lenders?

It is important for lenders because it confirms that the property value supports the loan amount, reducing financial risk and ensuring safe lending decisions.

What is included in home appraisal cost service?

The service includes property inspection, market comparison, condition review, neighborhood analysis, and a final official report showing fair market value.

How is home appraisal cost different from online valuation tools?

It is different because it involves a real physical inspection and expert judgment, while online tools only use data models, making appraisal far more accurate and lender-approved.

How Investment Property Appraisals Work in Residential Real Estate

Investment property appraisal showing rental income, occupancy, market demand, comparable sales, and property value

Investment property is where the whole real estate decision actually starts in the residential rental world. Before any deal moves forward, before any mortgage lender gives approval, and before any buyer feels confident, there is one thing that quietly controls everything: the appraisal.

With an property, it is never just about how nice the place looks or how big it feels. It always comes down to something much more practical. How much money can it realistically make in the rental housing market, and what would a buyer actually pay for it today if everything was put on the table?

That is exactly what the appraisal process tries to answer in a very structured, data-backed way.

What is Actually Happening in an Investment Property Appraisal

When dealing with a property, the appraisal is basically a reality check. It strips away emotion and focuses only on numbers, demand, and market behavior.

In simple terms, it keeps asking:

  • What is this property worth in today’s housing market
  • How much rent can this investment generate month after month
  • Does the income actually justify the price and the loan being requested

So instead of opinions, everything gets broken into facts that mortgage lenders can rely on.

How Value is Actually Formed for Investment 

For an investment, value is never picked randomly. It is built using two main approaches that work together like two sides of the same story.

Sales Comparison Approach (What the Market is Paying)

This approach simply looks around and asks: what are similar homes selling for right now?

For an investment, this means:

  • checking recent sales in the same area
  • comparing size, layout, condition, and upgrades
  • adjusting value based on differences
  • reflecting what real buyers are paying today

So if nearby homes are selling high, the property naturally gets pulled upward in value. If the market is slow, value adjusts down.

It is basically the market speaking through numbers.

Income Approach (what the property earns)

Now this is where things get more important for rentals.

With an investment, the focus shifts from “what it looks like” to “what it produces.”

This approach looks at:

  • rental income coming in every month
  • operating costs and maintenance
  • vacancy periods and risk
  • net operating income
  • long-term rental stability

This is the method mortgage lenders trust the most when the property is clearly meant for renting.

Because at the end of the day, income is what keeps the investment alive.

How investment property appraisal works using sales comparison, income approach, market analysis, and final value

Why Income Tells the Real Story of Investment Property

A property does not survive on appearance. It survives on cash flow.

So appraisers carefully study:

  • fair market rent in the area
  • rental demand and tenant interest
  • occupancy rates over time
  • how quickly units get filled
  • whether tenants stay or leave frequently

When rent is strong and occupancy is steady, the investment becomes much more valuable. When vacancies rise, value naturally drops even if the building itself looks perfect.

That is how sensitive rental value really is.

The Numbers that Quietly Decide Everything

In every property appraisal, a few financial terms carry most of the weight.

Gross Rent Multiplier (GRM)

This is a quick way to judge efficiency.

  • compares property price with annual rent
  • shows how many years it takes to “pay back” value through rent
  • helps quickly compare multiple property options

Lower GRM usually signals a stronger deal.

Net Operating Income (NOI)

This is where real strength shows.

For any investment property, NOI is calculated like this:

  • total rent collected
  • minus all operating expenses
  • excluding mortgage payments

The higher the NOI, the stronger the property is considered. It directly affects final valuation.

Rental Demand and Occupancy: The Heartbeat of Value

A property only performs if people actually want to live in it.

That is why appraisers pay attention to real-world signals like:

  • how fast rentals get filled in the area
  • whether demand stays consistent year-round
  • local job growth and migration trends
  • access to transport, schools, and services
  • how often units stay vacant

High occupancy means stability. And stability pushes investment value higher.

Low occupancy signals risk, and risk pulls value down.

Different Property Types, Different Valuation Behavior

Not every property is treated the same in appraisal.

Single-family rental homes

  • mostly judged by sales comparison
  • rental income used as supporting data

Multi Family Properties

  • heavily based on income approach
  • each unit contributes to total valuation

Small Apartment Buildings

  • strong focus on occupancy and NOI
  • long-term rental performance matters most

Manufactured Homes

  • stricter evaluation rules
  • condition and land ownership matter more

So every property category behaves differently during valuation.

What Mortgage Lenders are Really Trying to Protect

Mortgage lenders are not just approving a property. They are protecting their money.
So for any property, they focus on:

  • whether the value is realistic in the current market
  • whether rent can support long-term repayment
  • whether vacancy risk is under control
  • whether the property will hold value over time

If anything feels unstable, the lender becomes cautious, even if the property looks good on paper.

How the Full Appraisal Process Flows?

Here is how it typically unfolds for any property:

  • physical inspection of the property
  • collecting market and rental data
  • analyzing comparable sales nearby
  • calculating income performance
  • applying both valuation approaches
  • adjusting based on market conditions
  • final appraisal report sent to lender

Every step is designed to remove guesswork from the investment value.

How the Housing Market Quietly Changes Everything

A property is never isolated from the economy around it.

  • in a strong housing market, prices rise quickly
  • in a slow market, appraisers become conservative
  • in high rental demand areas, income value increases
  • in oversupplied areas, rent pressure reduces valuation

So even a strong property can lose value if the market weakens.

Timing matters more than most people realize.

Putting it all together 

Think of a property appraisal like a three-layer decision:

  • what similar properties are selling for
  • what rent the property can realistically generate
  • how stable the market and tenants are

All three layers combine into one final number that mortgage lenders trust completely.

Conclusion:

An investment is never valued based on guesswork or appearance. It is always shaped by income, demand, and market behavior.

When rent is steady, occupancy is strong, and demand stays healthy, the property naturally rises in value. When those weaken, value adjusts down, no matter how good the structure looks.

That is how residential real estate appraisal actually works in the real world.

Frequently Asked Questions

How does an investment property appraisal decide the final value?

An investment property appraisal decides value by combining rental income, comparable sales, and market demand to reflect what buyers would realistically pay today.

Why is income so important in investment property appraisal?

Income is important because an property is meant to generate cash flow, so rent, occupancy, and expenses directly determine its real financial strength.

What role does mortgage lenders play in investment property appraisal?

Mortgage lenders use the appraisal to confirm the property is worth the loan amount and that rental income can support repayment safely over time.

How does rental demand affect investment property value?

High rental demand increases property value because it reduces vacancy risk and ensures consistent rental income in the long term.

What is gross rent multiplier in property valuation?

Gross rent multiplier compares property price to annual rent to quickly judge how efficiently an property generates rental returns.

Why do occupancy rates matter so much for property?

Occupancy rates matter because they show how consistently a property earns income and how stable tenant demand is in the area.

How does housing market condition change investment property appraisal?

A strong housing market increases property value through higher comparable sales, while weaker markets reduce valuation expectations.

What makes small apartment buildings different as property?

Small apartment buildings rely heavily on rental income and occupancy, so their investment property value is mostly driven by income performance.

How is net operating income used in investment property appraisal?

Net operating income shows true profitability after expenses, making it one of the most important factors in property valuation.

What happens if an investment property appraisal comes lower than expected?

If the appraisal is low, mortgage lenders may reduce loan approval, require renegotiation, or ask for a higher down payment on the property.
How to Win a Property Tax Appeal and Cut Your Annual Tax Expenses

Property tax appeal guide for challenging overvalued property assessments and lowering annual tax expenses

Property tax appeal is something many property owners only think about when the tax bill suddenly feels too high. You open that notice, look at the number, and immediately feel it does not match what your property is actually worth.

That moment is usually where a property tax appeal service starts.

It is the process of telling the tax office, “I think my property has been valued too high, and here is why.”

And when done correctly, it can lead to real property tax reduction every single year.

Why does This Even Happen?

Let’s be honest. Tax assessments are not perfect.

They are based on estimates, old data, and general market assumptions. That means mistakes happen more often than people think.

Sometimes your property is:

  • valued like it was newly built when it is not
  • compared with better locations
  • measured incorrectly
  • or assigned wrong usage type

And that is exactly where a property tax appeal becomes important.

How Tax Value is Actually Decided

Most people never see the behind-the-scenes process.

The system usually looks at:

  • Recent sales nearby
  • Estimated construction costs
  • Land value in your area
  • Property size and condition
  • Rental or income potential

But here is the problem. These numbers are not always updated in real time.

So when market conditions change, your tax bill does not always change correctly.

That gap is where a property tax appeal works in your favor.

Market Value vs What They Think your Property is Worth

Think of it like this.

Market value is what someone is actually willing to pay today.

Assessed value is what the system believes your property is worth based on formulas.

Those two are not always equal.

When they are far apart, your taxes go up unfairly, and that is when a property tax appeal makes sense.

Property tax appeal process showing assessment review, market analysis, evidence gathering, filing, and tax reduction

The Appraisal Home Value Process in Real Life

When an assessor looks at your property, they are not always visiting it in detail.

They often rely on:

  • Records
  • Satellite data
  • Older inspections
  • Standard pricing models

This is called the property appraisal process, and it is where errors usually start.

A small mistake here can increase your yearly taxes for years.

Why a Market Value Appraisal Changes Everything

A market value appraisal for house is basically a second opinion.

A professional comes in and says, “This is what the property is actually worth in today’s market.”

It includes:

  • Real sale comparisons
  • Location changes
  • Condition of the building
  • Current demand

This becomes one of the strongest tools in a property tax appeal because it replaces assumptions with real numbers.

Commercial Property Owners Feel this More

If you own commercial space, you already know this is more complicated.

Because now the valuation is not just land and building. It also includes:

  • Rental income
  • Vacancy rates
  • Business demand
  • Future development potential

That is why commercial property tax appeals often require more documentation and deeper financial analysis.

A small mistake in income assumptions can significantly increase property tax liabilities.

Why your Tax Bill Affects your Real Money

Higher taxes do not just look bad on paper.

They directly affect:

  • Rental profit
  • Resale value
  • Investment returns

So a property tax appeal is not just paperwork. It is a financial correction.

Even a small reduction can save a large amount over time.

What Actually Helps You Win

Let’s keep it simple.

A strong case usually includes:

  • updated appraisal reports
  • proof of market value differences
  • correct property records
  • comparable sales in your area

These documents are what turn a weak claim into a successful property tax appeal.

Construction Cost Mistakes People Ignore

One hidden factor is construction costs.

Tax systems sometimes assume rebuilding your property would cost more than it actually would today. When this number is wrong, your valuation becomes inflated. Fixing this detail alone can support a stronger property tax appeal.

Simple Way to Understand the Appeal Process

Here is how it usually flows:

  • You receive your tax notice
  • You compare it with real market value
  • You gather supporting documents
  • You file a challenge
  • You wait for review or hearing

This is the basic property assessment appeal journey.

Where most people go wrong

Most rejections happen not because the case is weak, but because:

  • evidence is incomplete
  • deadlines are missed
  • comparisons are not relevant
  • reports are unclear

A properly prepared property tax appeal avoids these mistakes.

Why consulting help matters

Many people handle it alone and get stuck.

But property tax consulting helps because experts:

  • know how assessors think
  • understand valuation rules
  • prepare stronger documentation
  • improve chances of approval

It saves time and often increases results in a property tax appeal.

Conclusion:

At the end of the day, the goal is simple. You are not trying to avoid taxes. You are trying to make sure your property is taxed fairly based on real market value. That is what a property tax appeal is really about.

Frequently Asked Questions

Why should I file a property tax appeal?

Because your property may be overvalued compared to real market conditions.

How do I know if my taxes are too high?

If your assessed value is much higher than recent sales in your area, it may be overvalued.

Do I need an appraiser home value?

Not always, but a market value appraisal makes your case much stronger.

Can commercial properties reduce taxes more easily?

Yes, because valuation errors are more common in commercial assessments.

How long does the process take?

It depends on your region, but usually a few weeks to a few months.

Can commercial property owners benefit more than homeowners?

In many cases yes, because commercial valuations include income, rent assumptions, and market projections. it  can correct these complex calculations and reduce liabilities.

What documents should I prepare before filing?

You should gather appraisal reports, recent comparable sales, property records, and any correction evidence. These strengthen your property tax appeal significantly.

What is the difference between assessment and appraisal?

Assessment is done by the tax office using formulas, while appraisal is an independent estimate of real market value. A property tax appeal often relies on appraisal to challenge assessment.

Can construction cost errors affect my taxes?

Yes, if outdated or incorrect construction cost data is used, it can inflate your valuation. Fixing this is often part of a property tax appeal strategy.

Do I get a refund if my appeal is approved?

In many cases, yes. If your taxes were overpaid due to incorrect valuation, a successful property tax appeal may result in refunds or credits.

Why Commercial Real Estate Appraisal Matters Before Buying or Selling Property

Commercial real estate appraisal before buying or selling property

Commercial real estate appraisal is basically that moment where everything becomes clear in real estate. Before any big decision is made, before money changes hands, before a property gets listed or bought, this is the step that quietly decides what the property is actually worth in the real world.

Not what someone hopes it is worth. Not what an owner feels it should be. But what the market is ready to pay for right now.

That is what commercial real estate appraisers do. It pulls everything back to reality.

And in commercial property, that reality matters a lot more because the numbers are bigger, the risks are higher, and the mistakes are far more expensive.

What is Really Happening in Commercial Real Estate Appraisal

When people hear commercial real estate appraisal, it can sound technical, but in simple terms it is just a structured way of answering one question:

“What is this commercial property truly worth today?”

Commercial appraisal looks at income, location, condition, demand, and market trends. It studies how much money the property can generate and how strong the demand is in that area.

So instead of guessing, everything is broken down into real signals from the market.

For example, a shop in a busy commercial street will not be valued the same as a warehouse in a low-demand area. Even if both are the same size, the value changes because the earning potential is different.

That is the heart of commercial real estate appraisal.

Why this Step Matters so Much Before Any Deal

In real estate, most problems start when pricing is wrong.

Commercial appraisal prevents that.

Before selling or buying, this process gives a clear direction so no one is operating in confusion. Sellers avoid pricing too high and sitting on the market for months. Buyers avoid paying more than what the property can actually deliver in returns.

Even in situations like selling my house or selling home assets that include commercial units, this becomes even more important because one wrong number can affect the entire financial outcome.

And when someone is thinking about selling my home, especially if part of it has commercial use or rental space, knowing the true value becomes the difference between a smart deal and a stressful one.

Commercial real estate appraisal keeps everything balanced.

How is the Valuation Actually Understood?

It follows a clear flow that almost feels like building a full story of the property.
It usually starts with inspection. The building is checked properly, inside and out. Then comes the market study, where similar properties are compared. After that, income is analyzed, especially if rent is involved.

Then comes cost thinking, like how much it would take to rebuild the property today. Finally, all of this is combined into one final value.

So instead of one opinion, there are multiple layers of reality coming together.

That is why real estate appraisal is trusted by banks, investors, and serious buyers.

What Actually Affects Property Value in The Real World

There are always a few things that can push value up or pull it down. And in commercial real estate appraisal, these are always checked carefully.

  • Location and how active the area is
  • Type of tenants and rental consistency
  • Condition of the building and maintenance level
  • Market demand in that region
  • Future development plans nearby

Each of these things quietly changes how buyers think and how investors calculate returns.

For example, a clean building in a growing commercial zone can gain value even if it is not fully rented yet. On the other hand, an older building in a slow market may lose value even if it is fully occupied.

That is how sensitive real estate appraisal really is.

Why skipping valuation causes problems

A lot of people skip proper valuation and go straight into pricing. That usually leads to issues.

Sometimes a property stays listed for too long because the price is too high. Other times, it sells quickly but the owner realizes later that it was undervalued.

Both situations come from missing proper commercial real estate appraisal. Accurate valuation is also important when property owners need a Tax Appeal Appraisal to challenge an assessment that may not reflect current market value.

Common mistakes include:

  • Setting price based on emotion instead of data
  • Ignoring repair or upgrade costs
  • Assuming rent will always stay the same
  • Using outdated comparisons from the market
  • Not consulting a professional real estate appraiser

These mistakes look small at first but create big financial gaps later.

Commercial real estate appraisal process and property valuation

The Role of Professionals in the Process

Commercial appraisal becomes far more accurate when handled by trained experts.

A real estate appraiser is not just looking at the building. They are reading the market, studying trends, comparing similar properties, and calculating risk.

Professional real estate appraisers follow structured methods so the valuation can stand in front of banks, investors, and legal processes without issues. The same valuation expertise is also used in specialized situations such as a Date of Death Appraisal, where an accurate historical property value is required for legal or estate purposes.

There are also real estate appraiser requirements they must meet, which include training, licensing, and understanding local market laws.

This is why their reports carry weight in financial decisions.

How this Helps Both Buyers and Sellers

Commercial real estate appraisal is not just useful for one side. It helps both.

For sellers, it sets a realistic price so the property attracts serious buyers instead of sitting idle. For buyers, it gives confidence that the property is not overpriced.

It also helps investors decide whether the property is worth holding long-term or should be sold.

In simple terms, it answers questions like:

  • Is this a fair deal
  • Is the income strong enough
  • Is the price justified
  • What is the future potential

That is why appraisal in real estate is seen as a decision-making tool, not just a report.

Comparing properties to understand value better

One of the most practical parts of commercial appraisal is comparison.

Properties are studied side by side to understand what the market is doing.

Property TypeIncome StrengthMarket ConditionValue Trend
Office SpaceStrongStableSteady rise
Retail UnitMediumActiveModerate
WarehouseHighGrowingStrong rise

This kind of comparison makes pricing easier to understand and more transparent.

Commercial property valuation follows the same idea, especially when investors are looking at multiple options before making a decision.

Why Timing Changes Everything

One thing that is often ignored is timing.

Commercial real estate appraisal is not fixed forever. Markets change. Interest rates shift. Demand rises or falls.

A property valued today might not hold the same number six months later.

That is why investors and serious buyers always look for updated valuation before making decisions.

Even small market changes can affect real estate appraisal results.

Emotional Thinking vs Real Market Thinking

Real estate often becomes emotional. Owners attach memories, effort, and expectations to a property.
But the market does not work on emotion.

Commercial real estate appraisal removes that emotional layer and focuses only on facts. Income, demand, condition, and future growth decide the value.

That is what keeps pricing fair across the industry.

Without this step, decisions become personal instead of financial.

Long-Term Thinking and Investment Growth

It is not only about buying and selling. It is also about long-term planning.

Investors use it to understand which properties are growing in value and which are slowing down.

It helps in deciding:

  • When to sell
  • When to renovate
  • When to hold
  • When to reinvest

This is where real wealth planning starts in real estate.

Simple Truth Behind Valuation

At the end of the day, real estate appraisal is about clarity.

It answers the question every buyer and seller actually cares about: what is this property really worth in today’s market.

Not last year. Not in the future. Right now.

That clarity is what makes deals smoother, faster, and safer.

Conclusion:

It is the foundation of smart property decisions and helps sellers avoid underpricing. It helps buyers avoid overpaying and helps investors stay confident in their choices.

Without it, the market becomes guesswork. With it, decisions become structured and clear.

That is why commercial real estate appraisal stays at the center of every serious commercial property transaction.

Frequently Asked Questions

What does commercial real estate appraisal?

It tells the real market value of a commercial property based on income, condition, demand, and location instead of assumptions or emotional pricing.

Why do buyers rely on commercial appraisal before purchasing?

Because it helps confirm if the asking price is fair and whether the property can actually generate enough return in the current market conditions.

Who usually performs real estate appraisal?

A trained and certified real estate appraiser who studies market data, inspects the property, and compares similar buildings to determine fair value.

Can real estate appraisal change over time?

Yes, it can change based on market trends, interest rates, local development, and demand shifts in the surrounding area.

Why is location so important in commercial real estate appraisal?

Because location directly affects customer traffic, rental income potential, and long-term demand, which all influence property value.

Is real estate appraisal needed for loans?

Yes, banks require it to make sure the property value supports the loan amount and reduces financial risk for lending institutions.

How does rental income affect property value?

Higher and stable rental income usually increases property value because it shows strong earning potential for investors.

What happens if appraisal value is lower than expected?

The seller may need to adjust price, improve the property, or renegotiate, while buyers may use it to secure better terms.

How often should a property be appraised?

It is usually done every few years or whenever major financial decisions, refinancing, or market changes occur.

What is the biggest benefit of commercial real estate appraisal?

The biggest benefit is clarity, it removes guesswork and helps every decision be based on real market data instead of assumptions.

The Hidden Value Most Couples Miss in Divorce Settlement Appraisals

Divorce settlement appraisal showing a property valuation report, house model, and legal documents for fair settlement

Divorce settlement appraisals often get treated like just another legal step in the background of a separation. Something to “tick off” and move on. But in reality, this is where most of the financial fairness is either protected or completely lost.

Because once emotions enter the picture, numbers start getting distorted. And when numbers are off, the settlement quietly becomes uneven without anyone noticing right away.

That is why divorce settlement appraisals end up carrying more weight than most people expect. They decide who gets what, who buys out whom, and what the real financial outcome actually looks like.

Why Divorce Settlement Appraisals Quietly Decide the Outcome

At the core, divorce settlement appraisals are not about paperwork. They are about grounding everything in real market value instead of personal perception.

What usually happens is simple:

  • One side believes the home is worth more
  • The other side disagrees
  • Online estimates create more confusion
  • Negotiations get stuck

And suddenly, a single divorce property appraisal becomes the biggest conflict point.

A proper valuation cuts through all that noise and brings one shared number both sides can work with.

The Part Most People Don’t See: Hidden Value Shifts

One of the biggest blind spots in appraisals is how many small details quietly change the final value.

Not obvious things. Subtle things.

Like:

  • A kitchen upgrade done years ago but never documented properly
  • A neighborhood that has recently increased in demand
  • Small structural improvements that actually add long-term value
  • Repair issues that reduce value but are ignored in discussions
  • Rental potential that one side completely overlooks

These things don’t feel big individually, but together they can shift the valuation significantly.

And that’s where most disagreements start.

When Emotions Start Controlling the Numbers

Homes are not just assets. They carry memories, routines, and emotional attachment. That is exactly why divorce settlement appraisals become sensitive.

Because emotion changes perception.

One side may feel:

  • The home is “worth more than market value”
  • The property should not be sold at current prices
  • The investment of time and money should be fully recognized

But the market does not adjust for emotion.

It only responds to demand, condition, and real comparable sales.

That gap between feeling and fact is where conflict usually lives.

Why valuation ethics matter more than people realize

Valuation ethics are what keep the entire process stable.

Without them, appraisal becomes opinion. And opinion cannot be used in legal or financial decisions.

Strong valuation ethics mean:

  • No favoring either party
  • No emotional influence
  • No pressure-based adjustments
  • Full transparency in how numbers are calculated

In divorce settlement appraisals, this neutrality is what makes the final value defensible and usable in real settlement discussions.

Divorce settlement appraisal with property valuation documents, calculator, house model, and settlement analysis

Replacement cost appraisal: the part most people ignore

A replacement cost appraisal is often not talked about enough in divorce situations, but it adds an important layer of understanding.

Instead of asking “what is it worth today,” it asks:

“How much would it cost to rebuild this property from zero?”

That shift in thinking reveals:

  • Whether the property is underinsured or overinsured
  • How much structural value exists beyond land price
  • Whether market price reflects real rebuilding cost

It doesn’t always decide the settlement, but it gives a deeper perspective that helps avoid undervaluation.

The Role of a Real Estate Appraiser for Divorce Cases

A real estate appraiser for divorce is not just a property evaluator. They act more like a neutral translator between two conflicting viewpoints, which is why a professional Divorce Appraisal can provide an objective foundation for settlement discussions.

Their job usually includes:

  • Inspecting the property in detail
  • Studying recent comparable sales
  • Adjusting value based on condition and location
  • Removing emotional bias from the calculation
  • Delivering a report that can stand in legal discussions

In most cases, they become the reason negotiations actually move forward instead of staying stuck.

How home appraisal for divorce shapes settlement decisions

Home appraisal for divorce is often the turning point in the entire process.

Because once the value is clear, decisions become much more structured:

  • Whether one party buys the other out
  • Whether the property should be sold
  • How equity will be divided
  • What refinancing looks like

Before the appraisal, everything is assumption. After it, everything becomes negotiation based on facts.

The Simple Breakdown of Divorce Settlement Appraisals

Here’s how divorce settlement appraisals usually unfold in real situations:

Property Inspection Stage

  • Physical walk-through of the home
  • Checking condition, upgrades, and damages
  • Recording all visible factors affecting value

Market Comparison Stage

  • Studying similar properties sold nearby
  • Matching size, location, and condition
  • Adjusting for current market demand

Final Valuation Stage

  • One clear market value is calculated
  • Supporting evidence is attached
  • A structured report is prepared for legal use

It sounds technical, but in practice, it’s about creating clarity where there is disagreement.

Emotional pricing vs professional valuation

SituationEmotional ThinkingProfessional Appraisal
Value perceptionBased on memory and attachmentBased on market data
Decision makingConflicted and biasedStructured and neutral
OutcomeOften disputedLegally usable
StabilityLowHigh

This is exactly why divorce appraisals are never left to guesswork in serious cases.

Mistakes that quietly damage settlement outcomes

A lot of problems come from avoidable choices:

  • Relying on online estimates instead of real inspection
  • Ignoring repairs or condition changes
  • Choosing someone without proper certification
  • Delaying the appraisal until late in negotiations
  • Letting emotions influence property value discussions

Each mistake adds friction and slows down closure.

Timing changes everything in valuation

Markets move constantly. A property value is never fixed for long. A valuation done at the wrong time can lead to an outdated settlement number. Similar timing considerations can also matter when a property is being evaluated for a Tax Appeal Appraisal, where current and well-supported valuation evidence can be important.

In divorce settlement appraisals, timing affects:

  • Buyer demand in the area
  • Interest rates and lending conditions
  • Local development and infrastructure changes
  • Seasonal buying patterns

A valuation done at the wrong time can lead to an outdated settlement number.

Why courts rely heavily on appraisal reports

In legal situations, divorce settlement appraisals often become one of the strongest pieces of evidence.

Because they provide:

  • Neutral third-party valuation
  • Structured reasoning behind numbers
  • Market-backed justification
  • Reduced room for dispute

When both parties cannot agree, courts trust documented valuation over personal opinion.

Simple Ways to Avoid Settlement Delays

  • Get appraisal done early, not at the end
  • Use certified professionals only
  • Keep financial expectations realistic
  • Review multiple comparable sales together
  • Stay transparent throughout the process

These steps reduce conflict and make the process smoother for both sides.

Frequently Asked Questions

Why are divorce settlement appraisals so important in separation cases?

Because they create a neutral and factual property value that both parties can rely on, removing emotional disagreement and making settlement discussions more balanced and structured.

How does a home appraisal for divorce affect who keeps the property?

The home appraisal for divorce sets the fair market value, which is used to calculate buyout amounts and decide whether one party can realistically retain ownership.

What role does valuation ethics play in divorce cases?

valuation ethics ensure the appraiser stays completely neutral, avoids bias, and provides an honest valuation that can be trusted in legal and financial decisions.

Why is replacement cost appraisal sometimes considered?

Because it shows the cost of rebuilding the property, helping understand real structural value beyond just market pricing, especially for insurance and asset clarity.

Can divorce appraisals be challenged in court?

Yes, but only if there are clear issues in methodology or bias. Otherwise, professionally conducted appraisals are usually accepted as strong evidence.

What happens when both parties disagree on valuation?

A second appraisal may be requested, or courts may average values or appoint an independent expert to finalize divorce settlement appraisals.

Is a real estate appraiser for divorce necessary in every case?

Not always legally required, but highly recommended because it reduces disputes and ensures a fair, structured valuation process.

How does home appraisal in divorce influence selling decisions?

Home appraisal in divorce helps determine whether selling is financially beneficial or if a buyout is more practical based on equity value.

Why do professional appraisals differ from online estimates?

Because online tools don’t inspect property condition, legal context, or local market adjustments, while professional divorce settlement appraisals include all of these factors.

What is the biggest mistake people make during appraisal?

Letting emotion influence expectations instead of trusting market-based valuation, which leads to conflict and delays in final settlement.

Desktop Appraisal vs Full Appraisal: Which One Is Right for You?

Desktop appraisal vs full appraisal showing property valuation differences

Desktop appraisal is basically the quick way of knowing what a property is worth without anyone going out to physically check it. No site visit, no walking around the house, no inspection in person. Everything is done from a desk appraisal using records, online data, maps, and recent property sales.

That is why desktop appraisal is getting so common now. It’s fast, it’s simple, and it helps banks and lenders make decisions without waiting days for a full inspection.

Desktop home appraisal is just a quick value estimate based on data that already exists.

What is a Desktop Appraisal?

A desktop appraisal is a property valuation done without visiting the property at all. Everything is handled through a computer using available information.

How it actually works in real life

  • Property details are taken from official records
  • Nearby recent sales are checked and compared
  • Area demand and market trends are studied
  • Maps and satellite images are reviewed
  • A final value is estimated based on all of this

So basically, desktop appraisal is like putting together all the puzzle pieces of data and forming a property value.

No inspection, no physical checking, just information doing the job.

That is exactly why appraisal desks are fast and widely used.

Desktop Appraisal vs Full Appraisal

Now when people talk about desktop appraisal vs full appraisal, it’s really a simple difference in approach.

Desktop appraisal 

  • No one visits the property
  • Everything is based on data and records
  • Very quick results, sometimes in 1–2 days
  • Lower cost
  • Used when risk is low and property is standard

So desktop appraisal is basically a quick estimate done from behind a screen.

Full appraisal 

  • Someone actually goes to the property
  • Checks inside and outside properly
  • Looks at condition, repairs, upgrades
  • Takes more time
  • Gives more detailed and reliable result

A full appraisal is more like a proper on-ground check.

So simply said, commercial desktop appraisal is quick thinking with data, and full appraisal is real-world inspection.

Comparison of desktop appraisal and full appraisal property valuation processes

When Desktop Appraisal is Used

A desktop appraisal is used when things are simple and decisions need to be fast.

Real-Life Situations

  • Loan pre-approval cases
  • Mortgage refinancing
  • Standard residential homes
  • Property portfolio reviews
  • Quick desktop home valuation updates

In these situations, desktop appraisal helps avoid delays and keeps things moving. For certain mortgage-related situations, a PMI Appraisal may also be needed when determining whether a property has sufficient equity for PMI-related decisions.

If the property is normal and there is enough data in the market, desktop appraisal is usually enough.

How Desktop Appraisal is Done

The process of desktop appraisal is actually very straightforward. Property valuation services can use property data, comparable sales, location information, and other records to develop a supported estimate.

Simple Step-by-Step Flow

  • Property data is collected from databases
  • Similar homes nearby are checked
  • Recent sales are compared
  • Location and demand are reviewed
  • A value is calculated using models

So no one is stepping out, no visit is happening.

That is why desktop appraisal can be done so quickly, sometimes within a day or two.

Everything is already available digitally, so it’s just about analyzing it.

Why Desktop Appraisal is Becoming Popular

There’s a very simple reason why desktop appraisal is growing so fast.

Real Reasons Behind It

  • People want faster loan approvals
  • Banks want quicker processing
  • Property data is easily available online
  • Cost needs to stay low
  • Everything is becoming digital

So instead of waiting for physical inspections, desktop appraisal gives a quick answer.

That is why many lenders now use desktop appraisal as the first step.

Benefits of Desktop Appraisal

A desktop appraisal has some very practical advantages.

Why People Prefer It

  • Fast results without delays
  • Lower cost compared to full appraisal
  • No need to schedule visits
  • Easy for handling many properties
  • Works well for standard homes

A desktop appraisal is especially useful when properties are common and easy to compare.

That is why it is widely used in modern banking and real estate systems.

Limitations of Desktop Appraisal

Even though desktop appraisal is useful, it has its limits.

Where It Can Fall Short

  • No physical inspection happens
  • Hidden damage may be missed
  • Renovations may not be recorded
  • Not ideal for luxury or unique homes
  • Depends fully on data accuracy

So sometimes desktop house valuation gives a good estimate, but not the full real picture. For situations where a property’s value needs to be supported during a tax dispute, a Tax Appeal Appraisal can provide a more appropriate valuation approach.

That is when a full appraisal becomes necessary.

Cost and Time Comparison

The difference becomes very clear when comparing both.

Simple view

TypeTimeCostVisit
Desktop appraisal1–2 daysLowNo
Full appraisal3–7 daysHigherYes

So clearly, desktop appraisal is the faster and cheaper option.

That is why it is often used when speed matters more than detail.

How to Decide Between the Two

Choosing between desktop appraisal and full appraisal depends on the situation.

When Desktop Appraisal is Enough

  • Property is standard type
  • Fast decision is needed
  • Market data is strong
  • Risk is low

In these cases, desktop appraisal works perfectly fine.

When full appraisal is better

  • Property is luxury or unique
  • Condition matters a lot
  • High-value transactions are involved
  • Renovation or damage needs checking

In these situations, full inspection is safer than relying only on desktop appraisal.

Desktop Appraisal in Today’s Market

The real estate world is moving fast, and desktop appraisal fits perfectly into that speed.

Why it is widely used now

  • Faster loan processing
  • Less workload for inspectors
  • Can handle large number of properties
  • Works well in digital systems

So now, desktop appraisal is not just a shortcut anymore, it is becoming a normal starting point.

Conclusion

A desktop appraisal is basically the quick and simple way of finding a property’s value using data instead of physical inspection. It saves time, reduces cost, and helps decisions move faster.

At the same time, full appraisal is still important when details and real condition matter.

But in everyday situations, desktop appraisal is often the first and fastest step people rely on.

Frequently Asked Questions

What is a desktop appraisal?

A desktop appraisal is a property value estimate done using data and records without visiting the property physically.

Is desktop appraisal accurate?

Yes, it is accurate for standard properties with good market data, but it may miss real physical conditions.

How fast is desktop appraisal done?

Usually within 1 to 2 days because it is based on existing digital information.

What is the main difference between desktop and full appraisal?

Desktop appraisal is done without visit, while full appraisal includes physical inspection.

When should desktop appraisal be used?

It is used for loans, refinancing, and quick desktop valuation property. 
Can desktop appraisal replace full appraisal?

No, because it does not include on-site inspection of property conditions.

What data is used in desktop appraisal?

It uses sales data, property records, market trends, and location analysis.

Is desktop appraisal cheaper?

Yes, it is cheaper because no physical inspection is needed.

What are the risks of desktop appraisal?

It may miss hidden issues like damage or upgrades not recorded in data.

Why is desktop appraisal so popular now?

Because it is fast, cost-effective, and helps banks make quicker decisions.

PMI Mortgage Tips First-Time Buyers Wish They Knew Earlier

PMI mortgage tips for first-time home buyers covering costs, calculation, removal, and mortgage insurance

PMI mortgage is one of those parts of home buying that quietly changes the monthly budget without much warning. PMI mortgage shows up when the down payment is lower than 20 percent and it gets added into the monthly payment. PMI mortgage insurance is not a one-time fee, it keeps running until enough equity builds in the home.

PMI mortgage is mainly there to protect the lender, not the buyer. PMI mortgage helps approval happen faster for people who do not have a large upfront amount. Mortgage without pmi can feel confusing at first, but once it is broken down simply, it becomes easier to understand and manage.

How PMI Mortgage Works in Real Terms

  • PMI mortgage gets added when down payment is low
  • It protects the  pmi lenders mortgage insurance from loan risk
  • PMI mortgage is included in monthly installment automatically
  • PMI mortgage stays until equity reaches required level

PMI mortgage is basically a safety layer for banks. When less money is paid upfront, lenders feel more risk, so PMI mortgage balances that risk. PMI mortgage allows more people to buy homes earlier instead of waiting years.

PMI mortgage is not permanent, but it is important to know it will be part of early pmi payments on how to remove mortgage insurance.

Why PMI Mortgage Affects Monthly Budget

PMI mortgage directly increases monthly cost, even though it does not increase ownership. PMI mortgage often becomes the hidden reason budgets feel tighter than expected.

  • PMI mortgage depends on credit score
  • It depends on mortgage loan pmi size
  • PMI mortgage depends on down payment percentage
  • PMI mortgage varies between lenders

PMI mortgage can look small at first, but over time it adds up. PMI mortgage can make two similar homes feel very different in monthly affordability.

How much PMI Mortgage Really Costs

PMI mortgage usually falls between 0.2 percent and 2 percent of the loan per year. PMI mortgage is divided into monthly payments and added to the mortgage bill.

  • PMI mortgage is higher with low credit scores
  • PMI mortgage is lower with higher down payment
  • PMI mortgage changes based on lender risk rules
  • PMI mortgage stays until equity improves

PMI mortgage may not look large monthly, but over years it becomes a noticeable part of total cost.

PMI mortgage cost and removal guide showing equity, loan balance, refinancing, and ways to reduce PMI

How PMI Mortgage is Calculated Simply

Mortgage PMI is based on loan-to-value ratio, meaning how much of the home is borrowed compared to its value.

PMI mortgage formula:

Loan amount × PMI rate ÷ 12 = monthly PMI mortgage

PMI mortgage reduces as the loan gets paid down. PMI mortgage is reviewed during refinancing or when property value increases.

How PMI Mortgage Gets Removed

PMI mortgage does not last forever and can be removed when equity reaches around 20 percent.

  • PMI mortgage ends automatically at set equity level
  • PMI mortgage can be cancelled after lender review
  • PMI mortgage can be removed through refinancing
  • PMI mortgage stops when loan balance drops enough

Mortgage insurance removal instantly reduces monthly payments and improves long-term savings. PMI mortgage disappears faster with extra payments toward principal.

Simple Ways to Avoid PMI Mortgage

PMI mortgage can sometimes be avoided completely with the right setup.

  • PMI mortgage avoided with 20 percent down payment
  • PMI mortgage avoided with special loan programs
  • PMI mortgage avoided with alternative lender structures
  • PMI mortgage avoided by higher upfront savings

PMI mortgage avoidance reduces long-term cost, but requires more money at the start.

Conclusion:

Primary mortgage insurance is added when down payment is low and helps lenders reduce risk. PMI mortgage increases monthly payments but makes home buying possible sooner for many people. PMI mortgage is temporary and can be removed with planning.

PMI mortgage should always be included in budgeting before choosing a loan. PMI mortgage becomes easier to manage once its purpose and timeline are clear. PMI mortgage is not just an extra cost, it is part of how modern home loans work.

Frequently Asked Questions

What is PMI mortgage in simple words and why is it added to home loans?

Property mortgage insurance is added by lenders when down payment is low. It protects the lender from risk and allows buyers to qualify for a home loan with less upfront money, making homeownership more accessible.

How much does PMI cost every month for a homeowner?

PMI mortgage usually costs between 0.2 percent and 2 percent of the loan annually, which is divided into monthly payments depending on credit score, loan size, and down payment percentage.

Can PMI mortgage be removed early before full loan completion?

PMI mortgage can be removed early once home equity reaches about 20 percent, or earlier if the property value increases or refinancing is done based on lender approval conditions.

Why do lenders require PMI mortgage on some loans but not others?

PMI mortgage is required when lenders see higher risk, usually when down payment is low. It is not needed when buyers invest 20 percent or more upfront, reducing lender exposure.

Is PMI mortgage the same as home insurance or property insurance?

PMI mortgage is different from home insurance. PMI protects the lender in case of default, while home insurance protects the property from damage, loss, or unexpected events.

Does PMI mortgage increase over time or stay fixed?

PMI mortgage usually decreases over time as loan balance reduces and equity increases. It does not typically rise unless loan terms change or risk profile changes significantly.

How is PMI calculated in most loan agreements?

PMI mortgage is calculated using loan amount, PMI rate, and time. The annual rate is applied to the loan and then divided into monthly payments added to the mortgage bill.

Can PMI mortgage be avoided completely when buying a house?

PMI mortgage can be avoided by paying at least 20 percent down payment or using specific loan structures that do not require mortgage insurance, depending on lender options.

What happens if PMI mortgage is not removed when equity increases?

PMI mortgage continues to be charged until requested removal or automatic cancellation happens. Without action, extra cost keeps adding to monthly payments unnecessarily.

Is PMI mortgage worth paying for first time home buyers?

PMI mortgage can be worth it because it allows earlier entry into the housing market without waiting years to save a large down payment, even though it increases monthly cost.

Avoid Tax Issues with a Proper Date of Death Appraisal

Date of death appraisal for accurate property valuation and tax planning

A date of death appraisal becomes the first real step when settling an estate because it locks in the property value at the exact moment someone passes away. This is not about today’s market, it is about that specific date, which is why a date of death appraisal is used in probate and legal tax filings.

What does a Date of Death Appraisal Really Mean?

A date of death appraisal is basically a snapshot of property value frozen in time. It shows what a house or land was worth on the day the owner passed away, not before and not after.

This is important because property prices move constantly, and only a date of death appraisal ensures legal accuracy during estate settlement.

What it includes

  • Market value at time of passing
  • Property condition at that exact date
  • Local real estate trends at that time
  • Comparable property sales from the same period

This is where property value assessment and appraised property value come into play, helping support a solid valuation report.

Why a Date of Death Appraisal is so Important in Probate

A date of death appraisal plays a major role in probate because courts rely on it to decide how assets are distributed and whether taxes apply.

Without a proper date of death appraisal, estate settlement can turn messy very quickly.

Key Reasons It Matters

  • Prevents incorrect tax calculations
  • Supports fair asset distribution
  • Reduces legal disputes among heirs
  • Ensures compliance with estate laws

It also helps answer common concerns like is inheritance taxable, since accurate valuation is the base of that calculation.

How property value is determined at the time of death

To establish a date of death appraisal, professionals study market conditions that existed on the exact date of passing.

This process includes:

Valuation steps

  • Reviewing similar property sales from that time
  • Checking property condition and maintenance level
  • Studying neighborhood demand during that period
  • Applying standard real estate tax valuation methods

This is how experts determine how to determine date of death value of property in a legally acceptable way.

A date of death appraisal ensures nothing is estimated based on guesswork or current prices.

Alternate valuation date rules and when it applies

Sometimes estates use an alternate valuation date instead of a date of death appraisal, which allows assets to be valued six months later.

This option is only used if it reduces estate taxes or benefits the overall estate.

When it is used

  • Property value drops after death
  • Market conditions change significantly
  • Tax savings become possible

Even then, a date of death appraisal is still usually required as the primary reference point.

Types of Appraisers Involved in Estate Valuation

Different professionals handle different parts of estate valuation depending on property type and complexity.

Residential appraiser

  • Handles homes and residential estates
  • Common in probate cases involving family property

Building appraisal

  • Used for commercial or mixed-use buildings
  • Includes structural and income analysis

Land appraisal services

  • Focus on raw land and development potential
  • Used in rural or agricultural estates

Appraisal companies

  • Provide full legal valuation reports
  • Handle complex estate portfolios

Each of these supports a strong and accurate date of death appraisal when required.

Assessed Value vs Market Value Confusion

Many estates get confused between assessed value and market value during probate.

TypeMeaning
Assessed valueGovernment tax value
Market valueReal selling price
Date of death valuationHistorical probate value

A date of death appraisal is closer to market value at a specific past moment, not tax-assessed numbers.

This difference is critical when handling property tax assessment or tax assessed value vs market value comparisons.

Date of death appraisal showing property valuation for probate and estate settlement

Cost of a Date of Death Appraisal and What Affects It

The date of death appraisal cost depends on how complex the property and estate are.

Factors Affecting Cost

  • Property size and condition
  • Location and market activity
  • Type of property involved
  • Level of documentation required

A simple residential date of death appraisal is usually more affordable than commercial estate valuation.

Common Mistakes During Estate Valuation

Mistakes in valuation can cause legal and financial issues later.

Avoid these errors

  • Using current market value instead of historical value
  • Skipping professional appraisal services
  • Ignoring property condition at time of death
  • Overlooking probate requirements

A properly done date of death appraisal avoids these problems completely.

Why Professional Valuation Makes Everything Easier

A proper date of death appraisal removes uncertainty from estate settlement.

Professionals use:

  • Historical market data
  • Legal probate rules
  • Physical property inspection
  • Comparable sales analysis

This ensures the estate process stays smooth and legally correct from start to finish.

Quick overview table

ConceptPurpose
Date of death appraisalLegal estate valuation
Alternate valuation dateOptional tax adjustment
Residential appraiserHome valuation expert
Property tax searchTax record verification
Appraised property valueMarket-based valuation

Conclusion

A properly handled date of death appraisal is the foundation of accurate estate planning, fair inheritance distribution, and correct tax reporting. Without it, estates risk disputes, delays, and unnecessary tax issues.

Frequently Asked Questions

What is a date of death appraisal and why is it required in estate settlement and probate valuation processes for property ownership transfer?

A date of death appraisal is a legal valuation that determines property worth at the exact time of death. It is required for probate so assets are divided fairly, taxes are calculated correctly, and legal ownership transfer is properly documented.

Who performs a date of death appraisal and what qualifications are required for residential and commercial estate valuation experts?

Certified residential appraisers or licensed valuation professionals perform these reports. They must understand probate law, real estate trends, and historical market analysis to produce legally accepted documentation.

Is inheritance taxable and how does a date of death appraisal affect estate tax calculation and legal compliance requirements?

Inheritance tax depends on jurisdiction, but a date of death appraisal determines estate value, which directly impacts whether taxes apply and how much is owed during probate settlement.

What is an alternate valuation date and when can it be used instead of a date of death appraisal in estate tax planning strategies?

An alternate valuation date allows assets to be valued six months after death. It is used only if it reduces estate taxes and is legally approved, but original valuation remains the primary reference.

How is property value determined using a date of death appraisal in house valuation for probate purposes and legal documentation?

It is determined by reviewing past market conditions, comparable sales, and property condition at the time of death. This ensures accurate historical value for probate court acceptance.

What factors influence date of death appraisal cost in residential and commercial property valuation services for estate planning?

Cost depends on property size, complexity, location, documentation needs, and whether the property is residential or commercial. More complex estates require more detailed valuation work.

Do estates require official house valuation for probate and how do appraisal companies support legal estate settlement processes?

Yes, most estates require official valuation. Appraisal companies provide certified reports that courts accept for probate, ensuring accurate asset distribution and legal compliance.

What is the difference between assessed value vs market value in property tax assessment and real estate valuation processes?

Assessed value is used for taxation by authorities, while market value reflects actual selling price. Neither replaces a date of death appraisal, which is based on historical value.

What happens if a date of death appraisal is incorrect in probate proceedings and estate valuation of personal property distribution?

Incorrect valuation can lead to tax penalties, legal disputes, delayed probate, and unfair inheritance distribution, making accurate appraisal essential for smooth estate settlement.

How to Remove PMI Insurance Faster and Save Thousands

How to remove PMI insurance faster and save thousands

PMI insurance is one of those extra costs that quietly adds up every month. Many homeowners don’t realize how much they’re paying over time or how quickly it can be removed with the right steps. Understanding how it works, when it ends, and how to speed up the process can save thousands without changing the loan itself.

This guide breaks everything down in a simple, practical way so the path to removing PMI insurance becomes clear and actionable.

What is PMI and Why It Exists

At its core, what is pmi comes down to lender protection. When a home is purchased with less than 20 percent down, lenders add private mortgage insurance pmi to reduce their risk.

This means:

  • The borrower pays monthly insurance
  • The lender gets protection if payments stop
  • The homeowner builds equity more slowly due to added cost

Typical pmi percentage ranges between 0.5 percent to 2 percent of the loan annually. That can translate into hundreds of dollars every month depending on the loan size.

How Much PMI Actually Costs

Understanding mortgage loan insurance cost helps show why removing it early matters.

Example Breakdown

Loan AmountPMI RateMonthly CostYearly Cost
200,0001%1672,000
300,0000.8%2002,400
400,0000.7%2332,800

Even with the cheapest pmi, the numbers stack up quickly over a few years.

When Does PMI Go Away Automatically

A common question is when does pmi go away without taking action.

Under the homeowners protection act, lenders must automatically cancel PMI insurance when:

  • The loan reaches 78 percent loan to value ratio
  • Payments are current
  • No additional liens exist

This rule comes from the pmi cancellation act, which ensures borrower protection and prevents lenders from charging indefinitely.

How to Cancel PMI Early

Waiting for automatic removal is not always the best move. There are faster ways to handle how to cancel pmi and reduce costs sooner.

Key Strategies

  • Reach 80 percent loan to value through payments
  • Request cancellation directly from the lender
  • Maintain a strong payment history
  • Avoid late payments or refinancing disruptions

Simple Process

  • Check current loan balance
  • Estimate home value
  • Submit cancellation request
  • Schedule appraisal if required

Taking these steps can speed up how to get rid of mortgage insurance by months or even years.

PMI removal checklist for saving on mortgage insurance

How to Drop PMI Faster with Smart Moves

Looking at how to drop pmi requires a mix of timing and strategy.

Smart Acceleration Methods

  • Make extra principal payments
  • Increase monthly payment slightly
  • Refinance when property value rises
  • Renovate to boost home value

Each of these helps reduce loan balance or increase equity, both of which impact PMI insurance removal. A house appraisal may also help establish the property’s current market value when determining whether sufficient equity has been reached.

Refinancing to Remove PMI

Refinancing is one of the fastest ways to eliminate PMI insurance, especially when home value increases.

When It Makes Sense

  • Property value has increased significantly
  • Interest rates are lower
  • Equity has crossed 20 percent

However, refinancing includes fees, so it only works if long term savings outweigh upfront costs.

PMI vs MIP: Know the Difference

Understanding mip vs pmi is important before making decisions.

FeaturePMIMIP
Loan TypeConventionalFHA
RemovalPossibleSometimes permanent
CostVariesFixed structure

PMI insurance can usually be removed, while MIP often stays for the life of the loan unless refinanced.

Can You Avoid PMI Completely

Some borrowers look for a no pmi mortgage option.

Options Include

  • 20 percent down payment
  • Piggyback loans
  • Lender paid PMI
  • VA loans

Each option has trade offs. For example, lender paid PMI increases interest rate, which can cost more over time.

Tax Benefits and Deductions

Many ask if is mortgage insurance tax deductible.

The mortgage insurance premium deduction has been available in certain years depending on income limits and tax laws. Checking current eligibility is important since rules change.

Even when deductions apply, the best financial move is still to remove PMI insurance as early as possible.

Quick Checklist to Remove PMI Faster

Action Plan

  • Track loan to value ratio regularly
  • Make extra payments toward principal
  • Monitor property value trends
  • Request cancellation at 80 percent threshold
  • Consider refinancing strategically

Following this checklist helps reduce reliance on PMI insurance and speeds up financial progress.

Common Mistakes That Delay PMI Removal

Avoid These

  • Waiting for automatic cancellation
  • Ignoring property value increases
  • Missing payments
  • Not requesting appraisal when eligible

Small delays can result in paying thousands more in PMI insurance than necessary.

Frequently Asked Questions

What is PMI insurance and why is it required?

PMI insurance is a monthly cost added to loans with less than 20 percent down. It protects lenders, not homeowners, and is required to reduce risk on low equity mortgages, which increases total borrowing cost significantly.

When does PMI go away on its own?

Under the homeowners protection act, PMI automatically ends when the loan reaches 78 percent of the original value, as long as payments are current and no other financial risks exist on the property.
How to cancel PMI early without refinancing?

To handle how to cancel pmi, request removal once equity reaches 20 percent, maintain a strong payment record, and provide proof through an appraisal if needed by the lender.

Is mortgage insurance tax deductible in current year?

The mortgage insurance premium deduction depends on tax laws and income thresholds. It has been available in some years but requires checking updated IRS guidelines before claiming benefits.

What is the difference between PMI and MIP?

The difference in mip vs pmi lies in loan type. PMI applies to conventional loans and can be removed, while MIP applies to FHA loans and may remain for the full loan term.

Can PMI be removed before reaching 80 percent equity?

Yes, in some cases lenders allow early removal if property value increases significantly, but this usually requires a formal appraisal and strong payment history.

What is the average PMI percentage?

The typical pmi percentage ranges from 0.5 percent to 2 percent annually based on credit score, loan size, and down payment, directly affecting monthly housing costs.

Are no PMI mortgage options worth it?

A no pmi mortgage can avoid monthly insurance costs, but may include higher interest rates or complex loan structures, making long term cost comparison essential before choosing.

How much does PMI add to monthly payments?

The mortgage loan insurance cost can add hundreds monthly depending on loan size and rate, making early removal of PMI insurance one of the most effective ways to save money over time.

7 Secrets to Accurate House Valuation That Save You Thousands

7 secrets for accurate house valuation and saving money

House valuation is one of those things that looks simple on the surface but quietly controls almost every financial decision in real estate. Whether someone is selling, buying, investing, or even handling taxes, everything starts from one point: house valuation.

And here’s the reality most people only learn later. If house valuation is wrong, everything after that becomes wrong too. Pricing, negotiations, taxes, even long-term returns get affected.

That’s why understanding house valuation properly is not optional. It is the foundation that protects money and prevents expensive mistakes that usually show up too late.

Secret 1: Value Is Built, Not Just Located

A strong house valuation is never just about where the property is. Location matters, yes, but it does not decide everything.

Real value is built through multiple layers that work together.

What actually shapes value:

  • Demand in the area right now
  • Condition of the property, not just age
  • Renovations and their real market impact
  • Nearby infrastructure and development
  • Buyer activity in that specific segment

Many people check a home value estimator and assume it is final. But that’s only a surface-level guess. Real house valuation always goes deeper than numbers on a screen.

Secret 2: The Market Always Tells the Truth

If there is one rule in house valuation, it is this: the market never lies.

What similar homes are selling for right now is the most honest indicator of value.

Why this matters so much:

  • Buyers don’t care about opinions, only prices
  • Market trends change quickly
  • Old data loses meaning fast

A proper house valuation is always based on recent, real transactions, not assumptions or outdated comparisons.

Secret 3: Professionals Don’t Estimate, They Analyze

A proper house valuation is never a guess. It follows structured methods that are tested and repeatable.

Experts don’t rely on emotion or rough thinking. They rely on systems.

Common valuation methods:

  • Market comparison approach
  • Cost replacement approach
  • Income or rental-based approach

When legal or financial accuracy is needed, a qualified appraisal becomes necessary. In official cases, only an irs qualified appraiser is trusted to produce a valid house valuation that can stand in legal or tax situations.

Secret 4: Taxes Can Quietly Change Everything

One of the most overlooked parts of house valuation is how deeply it affects taxes and inheritance planning.

People often only realize this when it’s already too late.

Important tax factors:

  • estate tax exemption 2025 may change what is tax-free
  • estate tax sunset 2025 could reduce exemptions in future planning
  • Incorrect valuation can increase tax burden significantly

Even gifting property requires accuracy. That is why an appraisal for gift tax purposes is often needed to keep house valuation legally safe and properly documented.

Key factors that affect accurate house valuation

Secret 5: Online Estimates Only Show Half the Picture

A big mistake in house valuation is trusting online tools as final truth.

They are helpful, but incomplete.

What they usually miss:

  • Interior upgrades and finish quality
  • Structural condition
  • Local demand differences street by street
  • Real buyer behavior in that area

Even when someone tries to appraise my house, what they get online is only a rough range, not a true house valuation that reflects real market conditions.

Secret 6: Land Issues Can Change Value Overnight

A house valuation is not just about the building. The land underneath often carries hidden value changes.

Small legal or boundary issues can shift pricing significantly.

Key factors include:

  • Property boundary accuracy
  • Zoning rules and restrictions
  • Survey clarity and updates
  • property line survey cost when disputes arise

In serious disputes, a real estate expert witness may be needed to explain and defend house valuation in legal proceedings.

Secret 7: Urgency Changes Everything in Value

A house valuation behaves very differently when a property is under financial pressure.

This is where real estate stops being normal and becomes urgent.

Common situations:

  • homes for bankruptcy
  • bankruptcy homes for sale
  • forced liquidation sales

In these cases, fair market value still exists, but actual selling prices often drop because time is limited and buyers know the urgency.

That is why house valuation must always consider context, not just numbers.

The Biggest Mistake People Keep Repeating

The most expensive mistake in house valuation is emotional pricing.

It sounds harmless, but it causes real financial loss.

People add emotional value:

  • memories attached to the home
  • money spent on renovations
  • personal expectations

But the market does not pay for emotions. It only responds to demand, condition, and data-based house valuation.

Fair Market Value Keeps Everything Grounded

Every serious house valuation eventually comes back to one thing: fair market value.

That simply means what a real buyer is willing to pay under normal conditions.

No pressure. No urgency. No emotional influence.

When house valuation aligns with fair market value, decisions become clearer, faster, and much safer financially.

Quick Comparison of Valuation Approaches

MethodAccuracy LevelWhen It Works Best
Online estimateLowQuick rough idea
Agent comparisonMediumBasic pricing decisions
Professional appraisalHighBuying/selling decisions
Legal valuationVery highCourt, tax, disputes

Each level of house valuation serves a different purpose depending on how serious the decision is.

Conclusion

At the end of the day, house valuation is not just a technical step. It is the starting point of every real estate decision that involves money.

When house valuation is accurate, everything else becomes easier: pricing, negotiation, selling, and even tax planning. When it is wrong, even a good property can turn into a financial mistake.

That is why treating house valuation seriously is not about theory. It is about protecting money, avoiding risk, and making decisions with clarity instead of guesswork.

Frequently Asked Questions

What hidden factors can silently impact house valuation without homeowners realizing it immediately?

House valuation can shift due to zoning changes, infrastructure projects, school ratings, neighborhood safety, and buyer demand patterns that are not always obvious at first.

Why is a qualified appraisal required instead of using a simple estimate for serious house valuation cases?

Qualified appraisal is needed because it provides legally accepted and verified house valuation used for tax reporting, legal disputes, and financial documentation with official credibility.
How do estate tax exemption 2025 changes influence house valuation in inheritance planning?

Estate tax exemption 2025 changes can reduce tax-free limits, making accurate house valuation essential for planning inheritance and avoiding unexpected tax obligations.

What role does property line survey cost play in determining final house valuation?

Property line survey cost matters because unclear boundaries can lower buyer confidence, while accurate surveys improve legal clarity and strengthen overall house valuation.

Why do bankruptcy homes for sale usually have lower house valuation compared to normal listings?

Bankruptcy homes for sale often have reduced house valuation due to urgency, financial pressure, and limited negotiation time, which forces quicker and lower-priced deals.

How does fair market value help in keeping house valuation realistic during buying or selling?

Fair market value ensures house valuation reflects real buyer behavior under normal conditions, preventing overpricing or underpricing caused by emotion or urgency.
When is a real estate expert witness needed in house valuation disputes?

A real estate expert witness is needed when house valuation becomes part of legal cases, inheritance conflicts, or disputes that require professional market validation.
What is the biggest long-term risk of relying on incorrect house valuation?

The biggest risk is financial loss through poor pricing decisions, either by selling below true value or overpricing and missing real buyers in the market.

How Trust Tax Rates Work: A Simple Guide for Beginners

How trust tax rates work with trust funds, property, tax planning, and estate assets

Trust tax rates are where most people get confused when they first step into estate planning. The idea sounds simple. Put assets into a trust, protect them, and everything becomes easier. But the moment income starts flowing, trust tax rates begin to play a major role in how much money is actually kept versus how much goes to taxes.

This is the part that is often overlooked. And this is exactly where better understanding leads to better decisions.

What a Trust Really Does

Think of a trust as a container. Assets go into it, and rules are attached to how those assets are managed and distributed.

Inside that structure:

  • A trustee manages everything
  • A beneficiary receives the benefits
  • The assets sit in what is commonly called a trust fund

This setup is widely used because it gives control, protection, and long-term planning advantages.

Why Trust Tax Rates Matter So Much

Here is the reality. trust tax rates are not designed like personal tax brackets. They are tighter, faster, and reach higher levels quickly.

That means:

  • Less income is needed to hit higher tax brackets
  • More income can be taxed at higher rates sooner

Simple Comparison

TypeTax Progression
IndividualGradual
TrustRapid

So when income stays inside the trust, trust tax rates can significantly reduce what remains.

How Income Is Handled Inside a Trust

Every trust generates income in some way:

  • Rental income
  • Investment returns
  • Business profits

Now the key question becomes: where does that income go?

Scenario 1: Income stays in the trust

  • It gets taxed using trust tax rates

Scenario 2: Income is distributed

  • It gets taxed in the hands of the beneficiary

This one decision alone can change the entire tax outcome.

Revocable vs Irrevocable Trusts Explained Simply

Revocable Trust

This is the flexible option.

  • Can be changed anytime
  • Income is reported on personal taxes
  • Often linked with living trust and taxes

There is no immediate impact from trust tax rates during the lifetime of the creator.

Irrevocable Trust

This is where things become more serious.

  • Cannot be easily changed
  • Becomes its own tax entity
  • Fully subject to trust tax rates

This is where planning matters the most.

Trust tax rates comparison showing income retained in a trust versus distributed to beneficiaries

Trust Identification and Filing Basics

Every trust needs to be recognized officially.

That is where:

  • trust ein number
  • trust identification number

come into play.

Without these:

  • Accounts cannot be opened
  • filing taxes for a trust becomes impossible

This is the administrative side, but it directly connects to compliance and penalties.

Property Inside a Trust

A large number of trusts are built around real estate.

That includes:

  • putting property into a trust
  • putting a house into a trust
  • transferring property into a trust

Why people do this:

  • Avoid probate
  • Maintain privacy
  • Simplify inheritance

But once the property generates income, trust tax rates step in again.

Can Property Be Removed From a Trust

This question comes up often: can you take a property out of a trust

The answer depends entirely on the structure.

  • Revocable trust → usually yes
  • Irrevocable trust → not so simple

Removing assets can trigger legal and tax consequences, especially under trust taxation rules.

Step Up in Basis and Why It Matters

This is one of the most important concepts to understand.

When assets pass through a trust, their value may reset.

Two key situations:

  • step up in basis revocable trust
  • irrevocable trust step up in basis

What it means:

  • Assets are valued at current market price
  • Capital gains tax is reduced when sold

This can protect a significant portion of wealth.

Trust Taxation vs Estate Taxes

These two are often mixed up, but they are not the same.

Trust Taxation

  • Ongoing
  • Based on income
  • Driven by trust tax rates

Estate Taxes

  • One-time
  • Applied at transfer of wealth
  • Part of broader estate taxes planning

Both need to be aligned properly.

Special Cases Like Special Needs Trusts

Some trusts are designed with specific purposes.

One example is:

  • special needs trust taxation

These trusts are structured carefully to:

  • Protect benefits eligibility
  • Provide financial support

And still follow strict taxation rules.

Estimated Tax Payments for Trusts

Trusts do not just wait until the end of the year.

They often require:

  • estimated tax payments for trusts

Why this matters:

  • Avoid penalties
  • Spread tax burden
  • Stay compliant

Ignoring this can increase overall costs quickly.

Role of the Trustee and Beneficiary

The structure only works when roles are clear.

Trustee:

  • Manages assets
  • Makes decisions
  • Ensures compliance

Beneficiary:

  • Receives income or assets

This relationship directly affects how trust tax rates apply.

Living Trust and Taxes Made Simple

A living trust is often the starting point.

During lifetime:

  • No separate tax
  • Income flows to personal return

This is where taxes on living trust stay simple.

After death:

  • It may convert into a taxable trust
  • trust tax rates begin to apply

Trusts and Inheritance Tax Planning

When inherited property is involved, a Date of Death Appraisal can help establish an accurate value for estate and tax-related purposes.

Trusts are often used to manage:

  • trusts and inheritance tax exposure

The goal is simple:

  • Reduce tax burden
  • Protect assets
  • Control distribution

But without proper planning, taxes can still be high.

Estate Planning Services and Strategy

Professional estate planning services are often used to:

  • Structure trusts properly
  • Align tax strategy
  • Avoid common mistakes

Because once income starts flowing, trust tax rates cannot be ignored.

Smart Ways to Handle Trust Tax Rates

Practical approaches:

  • Distribute income when possible
  • Avoid unnecessary accumulation
  • Choose the right trust type
  • Plan property transfers carefully

Each of these reduces pressure from trust tax rates over time.

Common Mistakes That Cost Money

  • Keeping too much income inside the trust
  • Ignoring trust tax rates early on
  • Incorrect filing taxes for a trust
  • Poor handling of property transfers

These mistakes are more common than expected and often expensive.

Frequently Asked Questions

What are trust tax rates in simple terms?

Trust tax rates are the tax brackets applied to trust income. They reach higher levels faster than personal taxes, which means income inside a trust can be taxed more heavily if not managed properly.

Why do trust tax rates reach higher levels faster?

Trust tax rates are compressed, meaning smaller amounts of income move into higher tax brackets quickly. This is why planning distributions becomes important for reducing total tax liability.

Do all trusts pay taxes the same way?

No, different trusts follow different rules. Revocable trusts pass income to the owner, while irrevocable trusts are taxed separately under trust taxation rules and structures.

What is a trust EIN number used for?

A trust ein number is used for identification when opening accounts and filing returns. It is essential for filing taxes for a trust and maintaining compliance with tax authorities.

Can property be removed from a trust easily?

It depends on the type of trust. Revocable trusts allow flexibility, but irrevocable ones are restrictive. The question can you take a property out of a trust depends on legal structure and terms.

How does step up in basis help reduce taxes?

A step up in basis revocable trust adjusts asset value to current market levels, which reduces capital gains tax when the asset is sold by beneficiaries after inheritance.

Are taxes on living trust complicated?

taxes on living trust are usually simple during the owner lifetime because income is reported personally. Complexity increases only when the trust becomes a separate taxable entity later.

What is special needs trust taxation?

Special needs trust taxation follows strict rules to ensure that beneficiaries can receive support without losing eligibility for government assistance programs or benefits.

Why are estimated tax payments needed for trusts?

estimated tax payments for trusts help avoid penalties and manage tax obligations throughout the year, especially when the trust generates regular income from assets or investments.

Do trusts help reduce estate taxes?

Trusts can reduce estate taxes when structured correctly. They are often used in combination with broader strategies to manage wealth transfer and minimize overall tax exposure.

How to Accurately Calculate the Value of Your Home in 2026

How to accurately calculate your home value in 2026 using market trends, comparable sales, upgrades, and professional appraisal

The value of your home—let’s be real—isn’t some number you pull out of the air. It’s not what your neighbor thinks it’s worth or that figure Zillow throws at you. In 2026, it’s a mix of market moves, smart tools, upgrades you’ve done, and yes, buyer behavior. Knowing it properly can save you a ton of money and headache.

A lot of people ask: How do I find the property value of my home? or What’s the current value of my property? Most get it wrong because they rely on guesses or outdated info. Let’s fix that. Here’s how to actually figure it out.

Why the value of your home matters right now

Let’s be honest: this number touches everything in your life if you own property.

  • Selling? It decides your asking price. Too high, nobody bites. Too low, you lose money.
  • Refinancing? Your lender cares about this.
  • Taxes? Yep, higher value can mean higher property taxes.
  • Insurance? Underestimating it could leave you undercovered.

Outdated assumptions about the value of your home? That’s a fast track to losing money or making bad choices.

What really drives the value of your home

Don’t be fooled—it’s not just the size of the house. It’s several moving pieces:

Location

  • Are buyers fighting to live in your neighborhood?
  • Any new developments, parks, or schools?
  • Accessibility: commuting matters more than ever.

Condition of the Home

  • Old roof or leaky plumbing? That counts.
  • Upgrades? Kitchens and bathrooms matter the most.
  • Structural issues? That can tank your home’s value fast.

Market Conditions

  • Is it a seller’s market or buyer’s market?
  • Interest rates influence what people can afford.
  • Local buyer sentiment—sometimes it’s not logic, it’s emotion.

Comparable Sales

  • Homes like yours that just sold nearby.
  • Square footage, rooms, condition—adjust for differences.

This is the first step to understanding how a house valuation is done.

Key factors affecting home value including location, property condition, comparable sales, market conditions, and upgrades

Step-by-Step: How to Value Your Home Without Guesswork

1. Start with a Baseline Estimate

Online tools give a quick home appraisal. Think of it as a rough first look—not gospel.

Search for:

  • most accurate home value estimator
  • current home values

It gives a number, but it doesn’t know your home’s quirks or charm.

2. Check Out the Competition

Look at homes that recently sold near you:

  • Same size, same number of bedrooms and bathrooms
  • Similar condition and age

This gives a realistic idea of the present market value of my home.

3. Adjust for What Makes Your Home Unique

No two homes are identical. Add or subtract for:

  • Renovated kitchen or bathrooms
  • Smart home or energy-efficient upgrades
  • Outdoor spaces or premium views

These tweaks can bump the value of your home higher.

4. Time It Right

Timing can be everything.

  • Seller’s market? You can price more aggressively.
  • Buyer’s market? Price strategically to attract offers.

Watching current market value of home trends is key—you can’t just price by last month’s numbers.

5. Bring in a Professional

A licensed appraiser gives the appraisal value of my house through:

  • Physical inspection
  • Market research
  • Local expertise

It’s essential for serious financial moves, like refinancing or bankruptcy appraisal.

Table: What Really Moves Home Value

FactorWhy It Matters
LocationBuyers pay premium for the right spot
ConditionFixing big issues adds serious value
Market TrendsKnowing timing prevents mistakes
Comparable SalesReal numbers from nearby homes
Upgrades & FeaturesSmart improvements add premium

Common Ways to Evaluate Your Home

  • Comparative Market Analysis: Real estate agents do this using local sales.
  • Automated Valuation Models: Online tools; fast, but not perfect.
  • Professional Appraisal: Most reliable, often required for loans or legal cases.

Use all three for the clearest picture.

Mistakes That Hurt the value of your home

  • Thinking emotionally: “I love it, so it must be worth more.”
  • Ignoring needed repairs—buyers notice.
  • Relying only on online tools—they don’t see everything.
  • Forgetting market timing—it changes fast.

Even one misstep can throw off your value of your home drastically.

Tech Makes It Easier, But Don’t Forget Human Insight

2026 tools are impressive:

  • AI valuation tools
  • Real-time market data
  • Satellite imagery and predictive models

They make it faster to find property value of my home, but nothing beats a professional check.

When Should You Recalculate?

  • Market shifts
  • Renovations
  • Preparing to sell or refinance
  • Economic changes

Keeping an eye on the current value of my house keeps decisions smart and informed.

Quick Checklist to Nail Home Value

  • Check online estimators
  • Review comparable sales
  • Adjust for upgrades
  • Analyze market trends
  • Get a professional appraisal

Follow this and your value of your home isn’t a guess—it’s a number you can trust.

Conclusion:

The value of your home changes constantly. Market shifts, your property’s condition, and buyer behavior all affect it. Figuring it out right takes a mix of tools, data, and expert advice. Do it properly, and every financial choice about your home becomes easier and safer.

Frequently Asked Questions

What’s the most accurate way to determine the value of your home?

A professional appraisal paired with recent comparable sales gives the truest picture. Online tools offer a starting point, but they fall short on details.

How often should the value of your home be calculated?

Check it yearly, or right after big renovations, market changes, or key financial moves like selling or refinancing.

Can online tools give the exact value of your home?

No, they just estimate based on broad data. Unique home features and local nuances need a pro’s eye for precision.

What increases the value of your home the most?

Location tops the list, followed by major kitchen or bathroom updates and top-notch condition throughout. 

Does renovation always increase home value?

Only if it matches buyer expectations. Over-improving can sometimes not pay off.

What is a bankruptcy appraisal?

A legal valuation of your home during bankruptcy to determine fair asset value.

How do market trends affect home value?

In a seller’s market, prices rise; in a buyer’s market, they drop. Timing matters.

Is appraisal value the same as market value?

Not exactly. Appraisal value is structured; market value depends on what buyers will actually pay.

What is the difference between assessed value and market value?

Assessed value is for taxes; market value is what you can sell the home for right now.

How can someone quickly estimate home value before selling?

Check online tools, look at recent nearby sales, and ask a real estate agent.

Do You Need a Divorce Appraisal? Here’s the Truth Lawyers Won’t Tell

Divorce appraisal showing property, business valuation, asset division, and financial fairness during a divorce settlement

Divorce appraisal is one of those things most people don’t think about until everything is already complicated. Then suddenly, it becomes the center of major financial decisions. Property, businesses, shared assets — everything hinges on knowing what things are actually worth.

What Is a Divorce Appraisal and Why It Matters

A divorce appraisal is a professional assessment of the value of assets during a divorce. This usually includes homes, real estate, and sometimes businesses.

It matters because courts and settlements rely on accurate numbers. Without it, decisions are based on estimates, opinions, or outdated values — which can cost thousands.

Key Things It Affects:

  • Property division
  • Buyout amounts
  • Negotiation leverage
  • Financial fairness

If the numbers are off, everything that follows is off.

Home Appraisal for Divorce: What Actually Happens

A home appraisal for divorce is not the same as a casual property estimate. It’s a formal evaluation done by a certified appraiser.

The process usually includes:

  • Property inspection
  • Market comparison
  • Condition assessment
  • Final valuation report

Why this matters:

  • A higher value means a higher buyout
  • A lower value reduces payout obligations

Important insight:

The person who controls the appraisal process often has an advantage. That’s something rarely discussed openly.

Home Appraisal for Divorce Settlement: Timing Is Everything

A home appraisal for divorce settlement directly impacts how assets are divided.

Timing can change outcomes:

  • Early appraisal = may not reflect current market
  • Delayed appraisal = can increase or decrease value significantly

Example:

ScenarioOutcome
Market risingLater appraisal benefits seller
Market fallingEarlier appraisal benefits seller

This is why timing isn’t random — it’s strategic.

How Do I Get My House Appraised for Divorce

When asking how do i get my house appraised for divorce, the process is simpler than expected — but choosing the right appraiser is critical.

Steps:

  • Hire a certified appraiser (not a real estate agent)
  • Ensure they have divorce case experience
  • Request a full written report
  • Share report with legal parties

Pro tip:

Never rely on a single valuation when large assets are involved. A second opinion can shift negotiations significantly.

Who Gets the Appraisal Report First

The question who gets the appraisal report first comes up more often than expected.

The reality:

  • The person who orders and pays for it usually receives it first
  • It can be shared later with the other party or court

Why this matters:

  • Early access gives time to challenge or accept the value
  • It can influence negotiation strategy before the other side reacts

Control of information equals control of timing.

Divorce appraisal illustrating fair property valuation, business assets, appraisal reports, and financial settlement decisions

What Happens After Appraisal

Understanding what happens after appraisal helps avoid surprises.

After the report:

  • Both parties review the valuation
  • Disputes may arise
  • A second appraisal may be requested
  • Negotiations begin based on the number

Possible outcomes:

  • Agreement on value
  • Settlement using appraisal
  • Court intervention if disagreement continues

The divorce appraisal doesn’t end the discussion — it starts the financial negotiation.

House Valuation for Divorce vs Market Price

A house valuation for divorce may differ from what the property could sell for.

Why:

  • Appraisal is based on fair market value at a specific time
  • Actual sale price depends on demand, urgency, and negotiation

Quick comparison:

FactorAppraisalMarket Sale
BasisData & compsBuyer behavior
FlexibilityFixed reportNegotiable
Timing impactHighVery high

This is where confusion happens. Many assume both are the same — they are not.

Business Valuation Divorce: The Hidden Complexity

A business valuation divorce is far more complex than property valuation.

It’s not just about current income. It includes:

  • Future earning potential
  • Assets and liabilities
  • Market position
  • Goodwill

Valuing a Business for Divorce: What Gets Included

When valuing a business for divorce, multiple elements are considered.

These include:

  • Revenue trends
  • Ownership structure
  • Intellectual property
  • Contracts and client base

Even small differences in valuation methods can lead to major financial gaps.

Business Assets in Divorce: What Counts

Business assets in divorce go beyond physical items.

They may include:

  • Equipment
  • Inventory
  • Brand value
  • Client relationships
  • Digital assets

This is where many underestimate value — especially in modern or online businesses.

Business Valuation Divorce Settlement: Where Conflicts Happen

A business valuation divorce settlement often leads to disputes.

Common issues:

  • One party undervaluing the business
  • Disagreement on future projections
  • Hidden income or assets

How it plays out:

  • Independent valuation experts may be brought in
  • Courts may step in if no agreement is reached

This is one of the most contested parts of divorce financials.

Appraisal vs Fair Market Value in Divorce

The difference between appraisal vs fair market value in divorce is subtle but important.

Appraisal:

  • Formal estimate by a professional
  • Based on structured methodology

Fair Market Value:

  • What a buyer is willing to pay in real conditions

Why this matters:

Even though appraisals aim to reflect fair market value, they are still estimates — not guarantees.

The Truth Most People Don’t Hear

Here’s what often goes unsaid:

  • Not all appraisals are equal
  • Timing can shift outcomes significantly
  • Control of the process can influence results
  • Second opinions can change everything

A divorce appraisal is not just a formality — it’s a strategic financial tool.

Frequently Asked Questions

What is a divorce appraisal and why is it important?

A divorce appraisal determines the value of shared assets like property or business. It ensures fair division and prevents one party from being financially disadvantaged during settlement negotiations.

How long does a home appraisal for divorce take?

A home appraisal for divorce typically takes a few days to a week depending on property size, complexity, and appraiser availability, but the report preparation may take additional time.

Can both parties get separate appraisals?

Yes, both parties can request their own appraisals. This is common when there is disagreement, and courts may consider multiple reports before making a final decision.

What happens if appraisals are different?

If valuations differ, negotiations continue or a third independent appraiser may be appointed. Courts can also intervene to determine the most accurate value.

Is a divorce appraisal legally required?

Not always required, but highly recommended. Without it, asset division may rely on estimates, which can lead to unfair financial outcomes.

Who pays for the appraisal in divorce?

Usually, the person requesting the appraisal pays initially, but costs can be shared or adjusted later as part of the final settlement agreement.

Can a business be undervalued during divorce?

Yes, businesses can be undervalued intentionally or due to poor assessment. That’s why hiring experienced valuation professionals is critical.

How is fair market value decided in divorce?

Fair market value is based on comparable sales, financial data, and current market conditions. It reflects what a buyer would reasonably pay at that time.

What if one spouse hides assets during valuation?

Hidden assets can be uncovered through financial audits and legal discovery. Courts may impose penalties if intentional concealment is proven.

Should a second appraisal be considered?

A second appraisal is often a smart move when large assets are involved. It provides leverage and helps ensure the valuation used is accurate and fair.

Avoid Costly Mistakes: Understand the 3 Types of Bankruptcies First

explaining the 3 types of bankruptcies: Chapter 7, Chapter 13, and Chapter 11

The 3 types of bankruptcies give clear paths out of debt trouble. People often wonder what is bankruptcy or what happens when you file for bankruptcy. 

Quick Bankruptcy Basics

Bankruptcy is a legal way to handle debts you can’t pay. A debtor definition just means someone owing more than they can manage. Courts step in to pause collections and sort things out fairly. Bankruptcy law makes sure creditors get something while giving debtors a fresh start.

Filings happen in US bankruptcy court or local states bankruptcy court. An automatic stop hits right away—no more calls or seizures. But pick the wrong type, and problems grow.

Breaking Down the 3 Types of Bankruptcies

Here are the main 3 types of bankruptcies, each for different folks.

Chapter 7: Wipe It Clean

First of the 3 types of bankruptcies, Chapter 7 sells off extra stuff to pay debts, then cancels the rest. Great for low earners buried in credit cards or medical bills. A quick check sees if your income fits; most keep basics like clothes and cars.

Process wraps in months. How does bankruptcy work here? Trustee grabs non-essentials, creditors split the cash, done.

Chapter 13: Pay Over Time

Second in 3 types of bankruptcies, Chapter 13 bankruptcy definition sets a 3-to-5-year payment plan. Keep your house or car while catching up. Steady job? This fits, as you pay what you can afford.

Court approves the plan after talks. Filing for bankruptcy stops home loss fast.

Chapter 11: Business Lifeline

Third of 3 types of bankruptcies, Chapter 11 bankruptcy helps companies reshape debts without shutting down. Big personal debts qualify too. Commercial real estate appraisal can also be important when business property needs to be accurately valued during financial restructuring.

Chapter 7 vs 11 bankruptcy? One ends it quick, the other rebuilds.

Chapter 12 for Farms

A bonus beyond 3 types of bankruptcies, Chapter 12 bankruptcy eases things for farmers hit by bad seasons. Like Chapter 13 but flexible for crop cycles.

Side-by-Side Look

FeatureChapter 7Chapter 13Chapter 11
Who It’s ForNo-income folksSteady paycheckBusinesses
What HappensSell assetsRepay slowlyRestructure
Time4-6 months3-5 yearsVaries
Keep Stuff?Basics onlyMostYes

This shows different types of bankruptcies at a glance.

Comparison of Chapter 7 liquidation, Chapter 13 repayment plan, and Chapter 11 bankruptcy reorganization

Bankruptcy Myths Busted

Look, ever hear that bankruptcy means you’re toast forever? Pure baloney—folks climb back strong in just a couple years flat. Swear it kills job hunts dead? Nah, laws hide your filing from most bosses once discharge lands. And that whopper about losing every dime you own? Forget it—across the 3 types of bankruptcies, exemptions shield your house, ride, and nest egg in Chapter 7 or 13.

Think only losers file for bankruptcy? Dead wrong—medical bombs or pink slips shove good people there every day. Declaring bankruptcy skips child support or tax hits too; those suckers hang on tight. Ditch these tales, chat a bankruptcy attorney, skip the freak-outs that drain your wallet dry.

Rebuilding After Bankruptcy

Bankruptcy lingers on reports 7-10 years, sure, but bury it with solid moves. Hit credit unions—they eat up comeback yarns over raw scores. Chapter 13 finishers from the 3 types of bankruptcies rebound quickest, payments screaming “reliable.” Grind steady, play smart, that money freedom? It’s knocking already.

Steps to File for Bankruptcy

Want to file for bankruptcy? Start simple.

  • Take free credit counseling online or by phone.
  • List all debts, income, assets—be honest.
  • Pick forms for your 3 types of bankruptcies choice.
  • Pay fee (around $300-400) and submit to court.
  • Go to a short meeting; answer questions.

How to file bankruptcy without mess? Get a bankruptcy attorney. They dodge pitfalls like wrong exemptions.

What happens when you declare bankruptcy? Stay kicks in, life calms, plan rolls.

Why See a Bankruptcy Attorney

Skip the lawyer, and cases flop. They know bankruptcy rules, fight for you, handle appraisal company for asset values. Costs pay back in saved stress. DIY tempts for how to file bankruptcy easy steps, but numbers say pros jack success to 80%. They coach you through that 341 grill session on how does bankruptcy work, blocking fraud red flags that nuke discharges for good. Straight up, their smarts flip mess to order, so you rebuild clean after declaring bankruptcy.

Conclusion:

A sharp bankruptcy attorney catches different types of bankruptcies mismatches quick. Don’t hide cash—courts catch it. Test income first for Chapter 7. Think twice on declaring bankruptcy; credit dips 7-10 years, but rebounds.

Frequently Asked Questions

What is bankruptcy really?

What is bankruptcy? Court help for bankrupt people owing too much. Stops harassment, discharges debts or sets payments. Fresh start awaits after. 

Name the 3 types of bankruptcies?

3 types of bankruptcies: Chapter 7 liquidates, Chapter 13 repays, Chapter 11 reorganizes. Matches personal or business needs perfectly.

Chapter 7 vs 11 bankruptcy—key differences?

Chapter 7 vs 11 bankruptcy: 7 sells everything fast; 11 keeps business running via new plans. Quick end vs long rebuild. 

What happens when you file for bankruptcy?

What happens when you file for bankruptcy? Collections freeze instantly. Trustee sorts debts; most vanish in eligible cases. 

Explain Chapter 13 bankruptcy definition?

Chapter 13 bankruptcy definition: Wage earners pay debts over time, save home/car. Court-guided plan based on extra cash. 

How to file bankruptcy easily?

How to file bankruptcy: Counsel, forms, court submit. Attorney guides through US bankruptcy court. Means test decides type.

Need a bankruptcy attorney always?

Bankruptcy attorney pros file right, protect assets among 3 types of bankruptcies. Avoid DIY dismissals. 

When to consider declaring bankruptcy?

Declaring bankruptcy after failed talks, endless bills. Weigh 3 types of bankruptcies vs settlement options first. 

Where’s the states bankruptcy court?

States bankruptcy court sits in federal buildings locally. Handles bankruptcy news, filings nationwide. 

Any tips on bankruptcy visual representation?

Bankruptcy visual representation like charts show debt drop post-filing. Tracks 3 types of bankruptcies outcomes clearly.

Struggling with Small Business Taxes? Discover Powerful Tax Appeal Strategies

Small business tax planning with deadlines, tax deductions, filing forms, and powerful tax appeal strategies

Small business tax can feel overwhelming, especially when deadlines, deductions, and compliance rules start piling up. Many business owners struggle not because taxes are impossible, but because they are unclear, constantly changing, and often misunderstood.

Running a business already demands attention on operations, growth, and customer satisfaction. Adding tax responsibilities into the mix makes it even harder to stay focused. That is why understanding how small business tax works and how to manage it strategically can make a significant difference.

This guide breaks down everything in a simple, practical way. 

What Is Small Business Tax and Why It Matters

At its core, small business tax refers to the taxes a business must pay on its income, employees, and operations. These taxes vary depending on structure, location, and revenue.

Key Areas Covered Under Business Taxes

  • business income tax on profits
  • Payroll taxes for employees
  • Sales tax depending on services or products
  • Self-employment tax for owners

Understanding these categories helps avoid penalties and keeps the business compliant.

When Are Business Taxes Due 2025

Missing deadlines is one of the most common issues in small business tax management.

Important Deadlines to Remember

  • Quarterly estimated taxes: April, June, September, January
  • Annual filing: Typically April 15
  • Extensions available but payments are still due on time

Knowing when are business taxes due 2025 helps prevent late fees and unnecessary stress.

Understanding Business Tax ID Number

A business tax id number is essential for tax filing and financial operations. It is also known as EIN.

Why It Is Important

  • Required for filing a business tax return
  • Needed to hire employees
  • Used for opening business bank accounts

Many business owners often ask how can i get a business tax id. The process is straightforward through official tax authorities and usually takes only a few minutes online.

Common Business Tax Forms You Should Know

Different businesses require different forms. Choosing the right business tax form ensures accuracy and compliance.

Examples of Common Forms

  • Sole proprietors use Schedule C
  • Corporations file Form 1120
  • Partnerships use Form 1065

Using the correct business tax form reduces the risk of audits and delays.

Small Business Tax Preparation Made Simple

Proper small business tax preparation is the foundation of stress-free filing.

Steps to Prepare Efficiently

  • Organize financial records monthly
  • Track income and expenses
  • Use a reliable business tax calculator
  • Keep receipts for all transactions

Consistent preparation makes small business tax filing easier and more accurate.

Business Expenses for Taxes: What Can Be Deducted

One of the biggest advantages of managing small business tax properly is deductions.

Common Deductible Expenses

  • Office rent and utilities
  • Marketing and advertising
  • Software and tools including business software tax write-offs
  • Travel and vehicle expenses

Example Table of Deductions

Expense TypeDeductibleNotes
Office RentYesFully deductible
Internet BillsYesBusiness portion only
Personal ExpensesNoNot allowed
Equipment PurchaseYesDepreciation may apply

Using business tax deductions effectively lowers taxable income and increases savings.

Smart tax strategies for small businesses including tax deductions, expense tracking, tax planning, compliance, and filing deadlines

How Business Tax Services Can Help

Managing small business tax alone can be risky, especially when laws change frequently.

Benefits of Professional Help

  • Accurate filing and compliance
  • Identification of hidden deductions
  • Time savings
  • Reduced audit risk

Reliable business tax services ensure that nothing important is missed. When tax-related property assessments become a concern, a Tax Appeal Appraisal can help support a more informed property tax review.

Small Business Company Tax vs Large Corporations

The small business company tax structure differs significantly from large corporations.

Key Differences

  • Lower compliance complexity
  • Simplified filing requirements
  • Flexible tax deductions

However, understanding taxes on businesses of all sizes helps in planning for growth.

Business Tax Return Deadline and Filing Tips

The business tax return deadline is not something to ignore.

Smart Filing Tips

  • File early to avoid last-minute errors
  • Double-check all entries
  • Use digital tools for accuracy
  • Keep backup documentation

Meeting deadlines ensures smooth handling of small business tax obligations.

US Business Tax Rate and Its Impact

The US business tax rate affects profitability and planning.

What to Know

  • Rates vary by structure
  • Corporate tax is fixed
  • Pass-through entities depend on personal tax rates

Understanding these rates helps plan for long-term financial stability and smarter small business tax decisions.

Look Up Federal Tax ID for Business

Sometimes businesses need to look up federal tax id for business records.

When This is Needed

  • Lost EIN documentation
  • Filing corrections
  • Financial audits

Keeping records organized avoids unnecessary delays.

Smart Strategies to Handle Small Business Tax Efficiently

Managing small business tax is not just about filing, it is about strategy. For businesses concerned about excessive property-related taxes, understanding the Property Tax Appeal process can also be an important part of managing overall expenses.

Practical Strategies

  • Automate bookkeeping
  • Review finances monthly
  • Separate personal and business accounts
  • Plan quarterly payments

Consistent management reduces surprises and builds confidence.

Conclusion:

Handling small business tax does not have to feel complicated or stressful. With the right systems, clear understanding, and proper planning, it becomes manageable and even predictable.

The key is staying organized, knowing deadlines, and using available deductions wisely. Small steps taken consistently can lead to better financial control and long-term success.

Frequently Asked Questions

What is small business tax and who needs to pay it?

Small business tax hits income over $400, freelancers to LLCs—self-employment 15.3%, payroll if staffed. Sole owners pay personal plus extra; plan quarterly always. 

When are business taxes due 2025?

Quarters Apr/Jun/Sep/Jan 15; annual Apr 15, 2026. Extensions need payments or 5% fees monthly—when are business taxes due 2025 searches spike for this reason. 

How can i get a business tax id?

IRS.gov free EIN online: Entity type, address, reason—instant. Banks/hires require business tax id number; sole skip sans staff quick. 

What are common business tax deductions?

Business tax deductions like office formula, 67c/mile, ads full, meals 50%—track apps to drop small business tax owed sharply. 

What is the business tax return deadline?

Apr 15 core, extend 6 months paid up—business tax return deadline misses add interest fast on quarters too. 

Do i need business tax services?

Business tax services yes over $100K or states—catch credits, $500 fee saves vs errors; software tiny ops fine.

What is included in business income tax?

Business income tax on profits post-deductions—net $400+ triggers self-employment; brackets 10-37% personal flow. 

How does a business tax calculator help?

Business tax calculator estimates liability from income/expenses quick—free IRS/TurboTax previews federal plus state easy. 

What are business expenses for taxes?

Business expenses for taxes cover rent prorated, marketing full, tools—no personal; apps categorize for audits safe. 

What is the us business tax rate?

Us business tax rate 21% corps, 10-37% pass-throughs less 20% QBI, states 6% avg—deductions make real lower smart.

Common Mistakes to Avoid When Filing Divorce Papers

Common divorce paper mistakes to avoid when filing, including incorrect forms, missing information, and costly delays

Divorce papers, sounds simple, right? Just some forms, fill them out, file them, done. But in reality, getting them wrong can slow things down, cost more money, and create stress you really don’t need.

Whether you’re wondering how to get a divorce, curious about how much does a divorce cost, or trying to figure out how to file for divorce in California, this guide will walk you through the mistakes people make all the time and how to avoid them.

Mistake 1: Using the Wrong Forms

Here’s the thing: not all divorce papers are the same. Every state has different forms and rules. Trying to use a random PDF or old form? Big mistake. Your divorce papers could get rejected, and then you’re back to square one.

Tip: Always use official sources to get divorce papers online. State court websites are your best friend.

Mistake 2: Leaving Fields Blank or Getting Info Wrong

It’s easy to rush through the forms and miss something—like your address, kids’ info, or financial details. Even a tiny mistake in your divorce paperwork online can mean delays.

Financial info is especially important if there’s property involved. Mistakes here affect divorce appraisal and settlements.

Tip: Slow down, double-check every section, and make sure nothing is left blank.

Mistake 3: Not Knowing the Costs

“How much does a divorce cost?” is one of the top questions. And honestly, it depends. Filing fees, mediation, appraisals, and lawyer help all add up.

ItemAverage Cost
Filing Divorce Papers$250–$450
Divorce Mediation Services$150–$300 per session
Divorce Appraisal$300–$600
Lawyer Assistance$1,000–$5,000+

Tip: Budget ahead. Sometimes paying a little more upfront saves money and stress later.

Mistake 4: Thinking You Always Need a Lawyer

Not every divorce needs a lawyer. If your case is simple, you can file divorce papers yourself. Yes, it’s possible to file for divorce without a lawyer. How to file for divorce in California by yourself is a valid option.

Tip: For uncomplicated cases, check online divorce services—they’re often cheaper and faster than hiring a lawyer.

Mistake 5: Forgetting Property Appraisals

If you own property, don’t guess its value. A proper divorce appraisal by a professional divorce appraiser is key. Knowing appraisal vs fair market value in divorce helps avoid disputes and ensures a fair settlement.

Tip: Don’t assume Zillow estimates are enough. Professional appraisals protect your interests.

Divorce paper filing checklist showing common mistakes, property appraisal, mediation, filing costs, and tips for a smooth divorce process

Mistake 6: Skipping Mediation

Mediation isn’t just optional—it can save time, money, and stress. Many think court is the only path, but divorce mediation services can help settle disputes amicably.

Tip: Courts often look favorably on couples who try mediation first.

Mistake 7: Trying to Get Divorce Papers from Friends or Random Sites

You might think, “I’ll just grab the forms online somewhere.” Nope. Only official sources give valid divorce documents that courts will accept.

Tip: Know where do you get divorce papers before you start. It’s worth doing it right the first time.

Mistake 8: Filing Incomplete Online Forms

Online filing is convenient. But if you skip a page, forget a signature, or miss supporting docs, your divorce paperwork online is incomplete. That means delays.

Tip: Make a checklist of everything the court requires before submitting.

Mistake 9: Not Knowing How to Start Divorce Proceedings

Some people don’t even know how to start divorce proceedings. Filing divorce papers is just step one. You also have to understand timelines, court appearances, and how mediation works.

Tip: Research your state’s steps carefully so nothing surprises you.

Mistake 10: Ignoring the Simple Things

It sounds silly, but forgetting deadlines, missing signatures, or not keeping copies happens all the time.

Tip: Keep copies of all divorce papers and supporting documents. Whether you file in court or online, always have a backup.

Quick Tips for a Smooth Process

  • Use online divorce services if your case is simple.
  • Double-check all divorce documents for accuracy.
  • Know how much does a simple divorce cost before starting.
  • Hire a professional divorce appraiser if property is involved.
  • Keep copies of all divorce paperwork online submissions.

Conclusion:

Divorce papers start the whole process of divorce. Courts demand exact details on assets, kids, and support. Rush them, and judges send everything back. Folks often ask where do you get divorce papers – county clerks or divorce papers online sites work, but verify state rules first.

Pick the right forms for your area. For how to file for divorce in California, use official Judicial Council versions. Free templates save money but check dates – old ones get rejected.

Frequently Asked Questions

What Are Divorce Papers?

Divorce papers are legal forms that end your marriage. They cover kids, property splits, support—everything big. Start there. 

How to Get Divorce Papers?

Grab divorce papers from state court sites or clerks. Good online divorce services work. Skip junk PDFs—they flop. 

How to File for Divorce in California?

Get forms from courts.ca.gov. Fill  them, file at divorce court, pay up, serve your spouse. Easy solo for simple stuff. 

Can You File Divorce Papers Online?

Yep. Many states take divorce paperwork online. Quick, no courthouse trips. Check your rules first. 

How Much Does a Divorce Cost?

Simple? $300–$500 for fees. Messy adds mediation, divorce appraisal. Lawyers? Way more. Keep it clean. 

Need a Lawyer for Divorce?

Nope, not always. How to file for divorce without a lawyer rocks for no-fight cases. Saves cash fast. 

What’s a Divorce Appraisal?

Pro values house, assets fair. Ends appraisal vs fair market value in divorce fights. Courts love it.

Where to Get Divorce Papers?

State courts or official sites. Divorce papers online from real spots only. No sketchy downloads.

Cheapest Way to Get a Divorce?

Self-file divorce papers online. Uncontested, cheap services. Under $500 done. Skip extras. 

How Long for Divorce Papers?

Weeks to months if simple. Fights drag it out. Clean divorce documents speed it up.